Categories
Accounts Receivable

Accounts Payable Outsourcing vs In-House: Which Is Better?

Paying suppliers on time sounds straightforward. But as a business grows, managing invoices, checking purchase orders, resolving discrepancies and tracking payment deadlines can become a significant administrative task.

An in-house accounts payable team gives you direct oversight of the process. Outsourcing allows an external provider to manage some or all of the work. Both approaches can help a business maintain accurate records and manage supplier payments, but they differ in cost structure, flexibility, internal workload and control.

So, which option makes more sense for your business?

The answer depends on how many invoices you process, how complex your purchasing arrangements are, what expertise you already have in your finance team and how much oversight you want to retain internally.

This guide compares accounts payable outsourcing and in-house processing to help you make an informed decision.

What Is Accounts Payable?

Accounts payable (AP) refers to the money a business owes its suppliers for goods and services purchased on credit. It is a key part of working capital management because the timing and accuracy of supplier payments affect cash flow, financial records and supplier relationships.


An accounts payable process typically involves:


  • Receiving invoices from suppliers.
  • Checking invoice details against purchase orders and delivery records.
  • Verifying prices, quantities, taxes and payment terms.
  • Obtaining approval from the relevant department or manager.
  • Recording invoices in the accounting system.
  • Scheduling payments according to agreed terms.
  • Reconciling supplier statements and resolving discrepancies.
  • Maintaining supporting documents for reporting and audit purposes.


When these activities are managed inconsistently, businesses may face duplicate payments, missed discounts, delayed supplier payments or inaccurate financial records.


The question is not simply who should process the invoices. It is how the business can manage the entire process accurately, efficiently and with appropriate financial controls.

What Is In-House Accounts Payable?

In-house accounts payable means managing invoice processing and supplier payments through your own employees and internal systems.


Depending on the size of the business, this work may be handled by a dedicated AP team, an accounts executive or a wider finance department.


The business remains directly responsible for allocating work, setting procedures, supervising employees and monitoring performance.

Advantages of in house accounts payable

Direct control over the process


Your employees work within your organisation and follow your internal procedures. Finance managers can monitor invoices, resolve exceptions and adjust priorities as business requirements change.


Easier coordination with internal teams


AP employees can communicate directly with procurement, warehouse staff, project managers and department heads. This can help resolve missing documents, incorrect quantities and disputed charges.


Familiarity with suppliers and business operations


An internal team can develop an understanding of supplier agreements, purchasing patterns, recurring expenses and the reasons behind unusual transactions.


Immediate access to financial information


When systems and reporting processes are well organised, internal teams can provide finance managers with updates on outstanding invoices, upcoming payments and supplier balances.


Greater flexibility for complex transactions


Businesses with frequent exceptions, specialised purchasing requirements or complicated approval arrangements may find it easier to manage these activities internally.

Disadvantages of in house accounts payable

Higher fixed staffing costs


Employing an internal team involves salaries, recruitment, training, employee benefits, software and other operating expenses. These costs continue even when invoice volumes fall.


Limited capacity during busy periods


A sudden increase in invoices can put pressure on a small finance team. Employees may need to work overtime, delay other tasks or spend less time resolving complex issues.


Dependence on individual employees


If invoice processing relies heavily on one person, absence or staff turnover can interrupt payments and create backlogs.


Ongoing training and process management


Employees need to understand the accounting system, approval procedures, supplier requirements and relevant compliance processes. Maintaining these standards requires management time.


Risk of weak internal controls


Smaller teams may struggle to separate invoice entry, approval and payment responsibilities. Without suitable checks, errors or unauthorised transactions can go unnoticed.

In-house AP can work well, but it requires sufficient staffing, reliable systems and clearly defined responsibilities.

What Is Accounts Payable Outsourcing?

Accounts payable outsourcing involves engaging an external service provider to manage agreed parts of the AP process.


The provider may handle invoice capture, data entry, purchase order matching, approval routing, supplier statement reconciliation, payment preparation and reporting. Some arrangements cover most routine AP activities, while others focus on specific tasks.


The business generally retains responsibility for its financial decisions, supplier relationships and the approval of payments, according to the agreed workflow.

Advantages of accounts payable outsourcing

More flexible operating costs


Instead of maintaining a full internal team, a business can pay for an agreed service based on its invoice volumes, transaction complexity and required support. The actual cost depends on the provider’s pricing model and scope.


Access to specialised expertise


An experienced provider may bring established processes, trained staff and familiarity with AP systems and controls. This can be particularly useful for businesses without a dedicated accounts payable function.


Capacity to handle changing invoice volumes


An outsourced team may be able to accommodate seasonal peaks or business growth without the same recruitment and training requirements as an internal team.


More time for internal finance priorities


By transferring routine invoice processing and reconciliations, your internal finance team can focus more on budgeting, cash flow management, financial analysis and business planning.


Standardised workflows


A well-managed provider can establish consistent procedures for invoice validation, approval tracking, exception handling and record-keeping.


Potential process improvements


An outsourcing partner may recommend workflow changes, reporting improvements or technology that reduces repetitive manual work. The benefit depends on the provider’s capabilities and the quality of implementation.

Disadvantages of accounts payable outsourcing

Less direct day-to-day oversight


Your employees may not be involved in every processing step. Clear reporting, approval rules and escalation procedures are therefore important.


Dependence on the service provider


If the provider experiences staffing, technology or operational problems, invoice processing may be affected. Service continuity and backup arrangements should be agreed in advance.


Data security considerations


Invoices can contain supplier bank details, commercial terms and other sensitive information. Businesses must assess how the provider stores, accesses, transfers and protects financial data.


Potential communication delays


An external team may need additional information from your employees to resolve invoice discrepancies. Without agreed response times and escalation routes, these queries can slow down processing.


Transition and integration work


Moving an existing AP process to an external provider may require data cleanup, system access, workflow mapping and employee training. The transition takes time and should be planned carefully.


Outsourcing can reduce internal workload, but it does not remove the need for oversight. The business still needs clear accountability, appropriate approvals and visibility into its financial obligations.

Accounts Payable Outsourcing vs In-House : Key Differences

The following comparison highlights the main considerations for businesses evaluating both models.

Factor In-House Accounts Payable Outsourced Accounts Payable
Staffing Employees hired and managed internally External provider supplies agreed processing capacity
Cost structure Salaries, benefits, training, systems and management overhead Service fees based on agreed scope and pricing
Daily oversight Direct supervision of employees Oversight through reports, service levels and agreed controls
Scalability May require recruitment or overtime as volumes increase May offer more flexible capacity, depending on the contract
Supplier coordination Direct access to internal departments Requires effective communication and escalation arrangements
Process expertise Depends on internal staff and training Depends on the provider’s experience and capabilities
Data access Managed through internal systems and permissions Requires secure access arrangements and data protection controls
Business continuity May be affected by absence or staff turnover Depends on the provider’s staffing and continuity arrangements
Process standardisation Developed and maintained internally May benefit from the provider’s established workflows
Best suited to Businesses needing close internal coordination or specialised processing Businesses seeking additional capacity, expertise or reduced processing workload

Neither model is automatically better. A well-managed internal team can outperform a poorly managed outsourced service, just as an experienced provider can improve a process that is struggling internally.


The right choice depends on the business’s requirements and the quality of the operating model.

Which Option Is More Cost-Effective?

Cost is often the first consideration when comparing in-house and outsourced AP. However, comparing an employee’s salary with an outsourcing fee does not provide a complete picture.


You need to consider the total cost of running the process.


Costs of in-house accounts payable


An internal AP function may involve:


  • Salaries, benefits and employer-related costs.
  • Recruitment and onboarding expenses.
  • Training and professional development.
  • Accounting software and workflow tools.
  • Office and administrative overheads.
  • Management time spent supervising the process.
  • Overtime or temporary staffing during peak periods.
  • Costs associated with errors, rework and delayed payments.


Some of these expenses may already be shared across your finance department, so the additional cost of AP processing will vary by business.


Costs of outsourced accounts payable


An outsourced arrangement may involve:


  • Monthly service fees or per-invoice charges.
  • Initial setup and transition costs.
  • Software or integration fees, where applicable.
  • Additional charges for complex transactions or exceptional requests.
  • Internal time spent reviewing reports and approving payments.
  • Costs of changing providers or bringing the process back in-house.


The provider’s fee should be assessed against the work included. A low headline price may not cover exception handling, supplier queries, reconciliations or detailed reporting.


How to compare the two models


Use the same period and service scope when calculating the total cost of each option.

For example, if your internal team processes 800 invoices a month, estimate the fully loaded cost of the staff time, systems and management required to handle those invoices. Then compare it with an outsourcing proposal covering the same activities and expected service levels.


Also consider invoice complexity. Processing 800 straightforward invoices is not equivalent to handling 800 invoices that frequently require purchase order checks, dispute resolution and multiple approvals.


A useful comparison includes both cost and performance measures:


  • Cost per invoice processed.
  • Average time from invoice receipt to approval.
  • Percentage of invoices processed without manual correction.
  • Number of overdue invoices.
  • Frequency of duplicate or incorrect payments.
  • Time required to resolve supplier queries.


These measures help you assess whether the chosen model is improving the process rather than simply shifting the cost elsewhere.

How Does Each Model Affect Payment Controls and Accuracy?

Accounts payable involves outgoing payments, so appropriate controls are essential regardless of who processes the invoices.


The most important distinction is not whether the work is performed internally or externally. It is whether responsibilities are clearly separated and transactions can be traced from invoice receipt to final payment.


Controls for in-house AP


An internal team should have documented procedures for invoice verification, approval limits, supplier changes and payment release.


Where practical, different people should be responsible for entering invoices, approving expenditure and authorising payments. If a small team cannot fully separate these duties, compensating checks such as independent reviews and bank statement reconciliation become more important.


Controls for outsourced AP


An outsourcing agreement should define which activities the provider can perform and which decisions remain with the business.


Consider establishing:


  • Role-based system access and permissions.
  • Documented invoice verification requirements.
  • Clear approval limits and escalation rules.
  • Independent authorisation of supplier bank-detail changes.
  • Business-owned or appropriately controlled payment authorisation.
  • Audit trails showing who entered, reviewed and approved each transaction.
  • Regular reconciliations and exception reports.
  • Procedures for reporting suspected fraud or data breaches.


A key principle: Outsourcing invoice processing does not mean giving up control over payment decisions. Businesses can outsource administrative work while retaining approval authority and appropriate access to their financial records.


The precise arrangements should reflect the organisation’s risk profile, systems and contractual requirements.

When Should You Keep Accounts Payable In-House?

In-house AP may be the better choice when your business needs close coordination between invoice processing and day-to-day operations.


Consider keeping the function internal if:


  • Invoice processing involves frequent operational decisions or complex exceptions.
  • Your procurement, inventory or project teams need immediate coordination with AP staff.
  • Your transaction volumes are consistently high enough to support a dedicated team.
  • You already have effective systems, trained employees and clear approval procedures.
  • Internal teams need to handle sensitive commercial information under tightly controlled arrangements.
  • You want direct responsibility for every stage of the process and have the resources to manage it properly.


For example, a manufacturing business with frequent goods receipts, inventory discrepancies and supplier negotiations may benefit from having AP staff closely connected to its procurement and warehouse teams.


Even then, it may be worth reviewing whether repetitive tasks can be automated or whether some processing activities could be outsourced without disrupting internal coordination.

When Should You Outsource Accounts Payable?

Outsourcing may be a suitable option when routine invoice processing is consuming too much internal time or the business lacks the capacity to manage AP consistently.


It may be worth considering if:


Your invoice volume is increasing


More suppliers, purchases and transactions can create a growing administrative burden. An external team may provide additional capacity without requiring immediate recruitment.


Your finance team is stretched


If employees spend most of their time entering invoices and chasing approvals, they may have limited capacity for analysis, reporting and planning.


You are experiencing invoice backlogs


Unprocessed invoices and overdue supplier payments may indicate that current staffing, workflows or systems are not meeting business needs.


You need more consistent processes


A provider with a suitable operating model may help establish standard procedures, tracking and reporting.


You want to avoid building a larger internal team


If AP workloads fluctuate, an outsourced arrangement may offer a more flexible alternative to maintaining additional full-time staff.


You need specialist support


A provider with experience in your accounting systems, invoice workflows or transaction environment may help improve processing without requiring your business to develop every capability internally.


Before outsourcing, however, identify the underlying cause of any delays. If invoices are routinely missing purchase orders or managers do not approve expenditure promptly, transferring the work alone will not solve the problem.

Is AP Automation an Alternative to Outsourcing?

Yes. AP automation is another option, although it serves a different purpose.


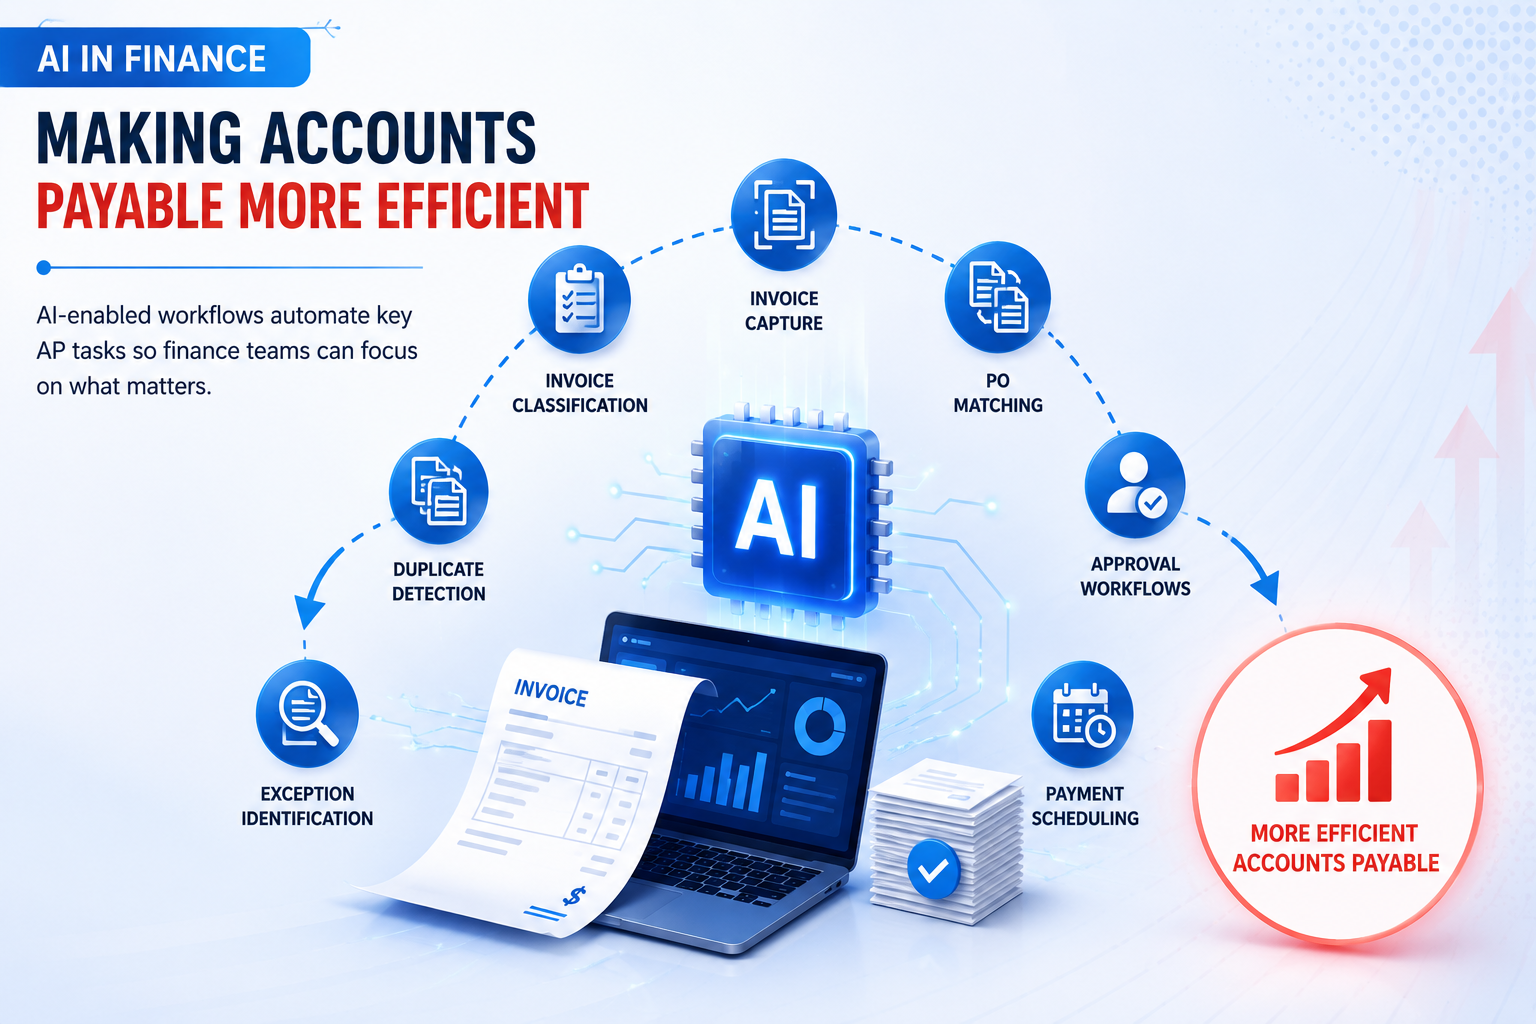
Outsourcing transfers agreed activities to an external service provider. AP automation uses technology to reduce manual tasks, such as invoice capture, data extraction, matching, approval routing and duplicate detection.


A business can automate AP internally, outsource the process or combine both approaches.

Approach How it works Main consideration
In-house manual processing Internal employees handle most tasks manually Direct control, but potentially more repetitive work
In-house AP automation Internal employees use software to streamline processing Technology investment, configuration and ongoing management
Outsourced AP An external provider performs agreed AP activities Provider oversight, service levels and data access
Outsourced and automated AP A provider uses technology to process invoices and manage workflows Requires clear accountability, integration and reporting

Automation can improve consistency and reduce manual data entry, but it does not eliminate the need to review exceptions, verify supplier changes or authorise payments appropriately.


Similarly, outsourcing does not guarantee automation. Ask providers which tools they use, which steps remain manual and how they measure processing accuracy.

Can You Use a Hybrid Accounts Payable Model?

Yes. A hybrid model combines internal oversight with outsourced processing or automation.


For example, a business could retain responsibility for supplier relationships, purchase approvals and payment authorisation while outsourcing invoice entry, reconciliation and routine query handling.


This approach can be useful when the business wants additional processing capacity but does not want to transfer every activity to an external provider.


A hybrid arrangement may include:


  • Internal approval of purchases and expenditure.
  • Outsourced invoice capture and validation.
  • Automated purchase order matching where supported.
  • Internal review of exceptions and disputed invoices.
  • Outsourced supplier statement reconciliation.
  • Internal authorisation of payment runs.
  • Regular reporting on outstanding invoices and process performance.


The success of this model depends on clearly defined responsibilities. Both internal employees and the service provider should know who handles each task, how exceptions are escalated and who has authority to approve transactions.

How to Choose an Accounts Payable Outsourcing Provider

If you decide to outsource, compare providers on more than their fees. The provider will be handling important financial records and potentially sensitive supplier information, so its processes and accountability matter.


Before making a decision, ask:


What exactly is included?


Clarify whether the service covers invoice receipt, data entry, purchase order matching, approval coordination, supplier queries, reconciliations and reporting.


How will performance be measured?


Agree on service levels for processing times, accuracy, query resolution and reporting. Establish how missed targets will be reviewed and addressed.


Which systems will be used?


Check whether the provider can work with your accounting software, procurement tools and approval workflows. Understand any integration costs or limitations.


How is data protected?


Ask about access controls, encryption, data retention, incident reporting, subcontractors and the handling of sensitive supplier information.


Who approves and releases payments?


Document the separation between invoice processing, expenditure approval and payment authorisation. Avoid arrangements that create unnecessary access or fraud risks.


How are exceptions handled?


Find out what happens when an invoice has incorrect details, a missing purchase order, a disputed amount or a potential duplicate.


What happens if you change providers?


Make sure the contract addresses access to your records, handover procedures, data export and continuity during transition.


A reliable provider should be able to explain its process clearly and provide reporting that allows your team to monitor performance.

Conclusion

Choosing between accounts payable outsourcing and in-house processing depends on your business’s transaction volumes, internal expertise, control requirements and growth plans.


An in-house team may be the better fit when direct coordination and specialised operational knowledge are essential, and the business has enough work and resources to support the function.


Outsourcing may be more suitable when invoice processing is stretching internal capacity, workloads fluctuate or the business wants access to additional expertise without building a larger team.


Automation and hybrid arrangements provide further options. In many cases, the strongest approach is to keep financial oversight and payment authority within the business while improving how routine processing is handled.


Before making a decision, assess your current cost per invoice, processing times, error rates and internal workload. Comparing these measures will help you choose a model that supports accurate payments, stronger controls and sustainable growth.

Frequently Asked Questions

It can be, particularly when a business would otherwise need to hire additional staff or maintain capacity for fluctuating invoice volumes. However, the outcome depends on transaction complexity, provider fees, transition costs and the internal time needed for oversight. Compare the total cost of delivering the same scope of work.

Depending on the agreement, a provider may handle invoice capture, data entry, purchase order matching, approval routing, supplier statement reconciliation, query management and reporting. Payment approval and release can remain with authorised employees within the business.

It can be managed securely when the provider has appropriate data protection measures, access controls, documented procedures and incident response arrangements. Businesses should assess these safeguards before sharing financial information and continue monitoring the service after implementation.

It may reduce errors when the provider introduces stronger validation, standardised workflows and suitable automation. However, results depend on invoice quality, system integration, staff expertise and exception handling. Accuracy should be measured rather than assumed.

Outsourcing transfers agreed AP tasks to an external provider. Automation uses software to reduce manual work. A business can use either approach independently or combine both, depending on its requirements and available resources.

Yes. A small business may outsource AP if invoice processing takes too much time, internal expertise is limited or payment administration is becoming difficult to manage. The service should be proportionate to the business’s transaction volumes and budget.

Not necessarily. A business can retain control through documented approval limits, restricted system permissions, independent payment authorisation, audit trails and regular performance reporting. The outsourcing agreement should clearly define the provider’s responsibilities and the decisions that remain with the business.

Categories
VIRTUAL CFO SERVICES

Fractional CFO Services for SMEs: What Do You Actually Get?

As a small or medium-sized business grows, managing finances becomes more complicated.

Revenue may be increasing, but that does not always mean profitability is improving. Cash flow can become harder to predict, hiring decisions carry greater financial risk, and business owners may struggle to understand which products, customers or services generate the strongest margins.

An accountant can help maintain accurate financial records and meet reporting requirements. However, growing businesses may also need someone who can interpret those numbers, identify financial risks and help management plan its next move.

This is where fractional CFO services can become valuable.

A fractional Chief Financial Officer (CFO) provides senior financial leadership on a part-time or flexible basis, giving SMEs access to strategic finance expertise without necessarily hiring a full-time CFO.

But what does that actually include? Does a fractional CFO manage cash flow, prepare financial reports, support fundraising or help improve profitability?

The answer depends on the engagement, but understanding the typical responsibilities can help you decide whether this service is right for your business.

What Are Fractional CFO Services?

Fractional CFO services provide businesses with access to an experienced finance leader for an agreed amount of time or scope of work.


Instead of employing a CFO full-time, an SME can engage a professional to support specific financial responsibilities, attend management meetings, review performance and guide important business decisions.


The arrangement may be monthly, project-based or structured around particular business requirements.


For example, a business might need regular cash-flow forecasting and management reporting. Another might need financial modelling before opening a new location or preparing for investment.


Typical fractional CFO services include:


  • Cash-flow forecasting and working capital management
  • Budgeting and financial planning
  • Management accounts and KPI analysis
  • Profitability and margin reviews
  • Financial modelling and scenario planning
  • Business growth and expansion planning
  • Fundraising and investor reporting
  • Financial risk management
  • Finance team oversight
  • Strategic decision support


The exact scope should be agreed at the beginning of the engagement. Some providers focus mainly on strategic advice, while others also coordinate reporting and oversee the wider finance function.

What Do Fractional CFO

The most useful way to understand fractional CFO services is to look at the work involved and the decisions it helps business owners make.


Cash-Flow Forecasting and Management


Cash flow is one of the first areas a fractional CFO may review.


A business can generate revenue and still experience financial pressure if customers pay late, supplier payments fall due before receipts arrive, or expansion requires more working capital than expected.


A fractional CFO can help develop cash-flow forecasts that show expected money coming into and leaving the business.


This may include:


  • Forecasting customer receipts and supplier payments
  • Reviewing payroll and operating expenses
  • Identifying potential cash shortages
  • Monitoring outstanding receivables
  • Assessing working capital requirements
  • Modelling the financial impact of new commitments
  • Reviewing short-term and longer-term cash requirements


For example, a business planning to recruit five additional employees may need to understand the impact on payroll, overheads and available cash before making the commitment.


A cash-flow forecast can help management assess whether the business can support the decision under different trading conditions.


The objective is not simply to report the current bank balance. It is to understand how the cash position could change and what decisions may be needed in advance.


Budgeting and Financial Planning


A budget gives a business a financial plan to work towards. However, a budget is only useful if management can compare actual performance against it and respond when circumstances change.


A fractional CFO can help SMEs prepare budgets based on their business objectives, expected revenue, operating costs and investment plans.


This can involve:


  • Preparing annual budgets
  • Setting departmental or business-unit budgets
  • Forecasting revenue and expenses
  • Reviewing actual results against budget
  • Investigating significant cost variances
  • Updating forecasts as conditions change
  • Aligning spending with business priorities


Suppose an SME plans to increase sales by 25% over the next financial year.


A fractional CFO can help assess what that target means for staffing, marketing expenditure, operating capacity and working capital.


If costs are increasing faster than revenue, the business can review its assumptions and adjust its plans rather than waiting until year-end to identify the problem.


Management Reporting and KPI Analysis


Financial statements explain what has happened financially, but business owners also need to understand why performance has changed and what to do next.


Fractional CFO services may include monthly management reporting, KPI dashboards and financial performance reviews.


Depending on the business, these reports may cover:

Financial area What it helps management understand
Revenue Whether sales are growing as expected
Gross margin How much revenue remains after direct costs
Operating expenses Where the business is spending money
Operating profit How effectively the business converts revenue into profit
Cash position How much cash is available
Receivables How much customers owe and when payment is expected
Working capital How effectively short-term assets and liabilities are managed
Budget variances Where actual performance differs from the plan

The value comes from interpreting the information, not simply producing another report.


For example, revenue may be increasing while gross margins are falling. A fractional CFO can investigate whether pricing, supplier costs, product mix or delivery expenses are contributing to the change.


This gives management a clearer basis for deciding where corrective action may be needed.


Profitability and Margin Improvement


Higher revenue does not automatically mean a more profitable business.


Some customers may require substantial support, certain services may carry higher delivery costs, and discounts may reduce margins more than management realises.


A fractional CFO can review profitability across products, customers, services, projects or business units, depending on the information available.


This work may include:


  • Analysing gross and contribution margins
  • Reviewing pricing structures
  • Identifying unprofitable products or services
  • Comparing customer profitability
  • Investigating cost increases
  • Assessing the financial impact of discounts
  • Reviewing overhead allocation
  • Identifying opportunities to improve financial performance


Consider a professional services business that has increased its client base but is struggling to improve its overall profit.


A profitability review may reveal that certain projects require considerably more delivery time than originally estimated.


Management can then review pricing, project scope and resource allocation.


The purpose is to help the business understand where its profits are generated and which commercial decisions could improve financial performance.


Financial Forecasting and Scenario Planning


Business decisions often involve uncertainty.


An SME may be considering a new location, a larger team, a product launch or an investment in new equipment. Each decision can affect revenue, costs, cash flow and profitability differently.


A fractional CFO can build financial models to compare possible outcomes before the business commits resources.


For example, scenario planning can help answer questions such as:


  • What happens if revenue grows more slowly than expected?
  • Can the business afford additional employees?
  • How would a supplier price increase affect margins?
  • What level of sales is required to cover additional overheads?
  • How much cash will expansion require?
  • What happens if a major customer pays late?


The work may involve preparing a base-case forecast alongside more optimistic and cautious scenarios.


This does not eliminate uncertainty, but it helps management understand the financial assumptions behind a decision and identify potential risks earlier.


Financial Strategy and Business Growth Planning


A fractional CFO can help connect financial performance with the wider business strategy.


This becomes particularly relevant when an SME is planning to enter a new market, expand its product range, invest in equipment or increase its workforce.


The CFO can assess the financial implications of the proposed plan and help management determine whether it is commercially viable.


This may include:


  • Evaluating expansion costs
  • Reviewing investment requirements
  • Assessing expected returns
  • Analysing pricing and margins
  • Comparing funding options
  • Reviewing business performance against growth targets
  • Preparing financial projections
  • Identifying financial risks


For instance, a business considering opening a second location may need to estimate setup costs, additional staffing, expected sales, operating expenses and the time required to reach profitability.


A fractional CFO can help bring these assumptions into a financial model so management can evaluate the proposal more clearly.


The final decision remains with the business owners, but it can be supported by a more structured financial assessment.


Fundraising and Investor Reporting


SMEs preparing to raise capital may need more detailed financial information than their regular accounting reports provide.


Potential investors and lenders may want to understand the business model, revenue assumptions, profitability, cash requirements and future financial performance.


Depending on the engagement, a fractional CFO may support:


  • Financial projections
  • Fundraising models
  • Cash requirements and funding plans
  • Investor reporting
  • Financial due diligence preparation
  • Management information packs
  • Scenario analysis
  • Meetings with investors or lenders


For example, a business seeking funding to expand may need to explain how the investment will be used, what additional revenue it could generate and how its financial position may change.


A fractional CFO can help prepare the underlying financial analysis and ensure that the assumptions are clearly documented.


However, fundraising support does not automatically include legal advice, tax advice or investment-banking services. These responsibilities should be clarified before the engagement begins.


Finance Team Oversight and Process Improvement


Some SMEs have an accountant, bookkeeper or finance manager but do not have senior financial leadership.


A fractional CFO can work with these existing employees to improve reporting, establish financial routines and strengthen the connection between accounting information and management decisions.


Depending on the agreement, this may include:


  • Reviewing month-end reporting processes
  • Improving the quality of management information
  • Establishing financial KPIs
  • Reviewing budgeting procedures
  • Clarifying reporting responsibilities
  • Improving financial controls
  • Coordinating with external accountants
  • Supporting the development of the finance team


For example, the internal accountant may be responsible for preparing monthly accounts, while the fractional CFO reviews the results, explains significant changes and presents recommendations to management.


This allows the business to retain its existing finance structure while adding senior financial guidance.

What Does a Fractional -CFO Deliver Each Month?

The deliverables depend on the provider, business complexity and agreed level of involvement. However, an ongoing engagement may include a combination of the following.

Deliverable Typical Purpose
Monthly management accounts review Understand financial performance and significant changes
KPI dashboard Monitor the measures most relevant to the business
Cash-flow forecast Assess expected cash movements and potential shortfalls
Budget variance analysis Compare actual performance against the financial plan
Forecast updates Adjust expectations based on recent results
Management meeting Discuss financial performance and decisions requiring attention
Action plan Assign next steps for addressing financial issues
Strategic finance advice Assess growth, hiring, pricing or investment decisions

Not every fractional CFO engagement includes every item.


For example, one provider may prepare the management accounts, while another may review information prepared by the client’s existing accountant.


Before signing an agreement, ask which reports will be produced, how often meetings will take place, who is responsible for preparing the underlying data and which decisions the CFO will support.

What Is Not Usually Included in Fractional CFO Services?

Understanding the limits of the service is just as important as understanding what it provides.


Fractional CFO services are generally focused on senior financial management, planning and decision support. They do not automatically replace every accounting or compliance service.


Depending on the provider, the following may sit outside the engagement:


  • Day-to-day bookkeeping
  • Routine transaction processing
  • Payroll administration
  • Statutory accounts preparation
  • Tax return preparation
  • Audit services
  • Legal advice
  • Routine accounts payable and receivable processing


Some providers offer these services through a wider finance or accountancy package, while others expect the business to maintain separate arrangements.


A fractional CFO may oversee or coordinate certain activities without personally performing every task.


For this reason, it is important to distinguish between financial leadership, accounting operations and statutory compliance when comparing service proposals.

Fractional CFO vs Accountant: What Is the Difference?

An accountant and a fractional CFO can work together, but their main responsibilities are different.

Area Accountant Fractional CFO
Primary focus Financial records, reporting and accounting requirements Financial strategy, planning and decision support
Historical performance Records and reports financial activity Interprets results and identifies implications
Cash flow May prepare cash information and reports Uses forecasts to support cash and funding decisions
Budgeting May assist with financial information Helps develop, monitor and revise budgets
Profitability Provides relevant financial data Analyses margins and commercial performance
Growth planning Supports accounting requirements Evaluates the financial impact of growth plans
Fundraising May prepare relevant financial records May develop projections and support financial preparation
Business decisions Supplies accurate financial information Helps management assess options and trade-offs

These responsibilities can overlap, and the precise division depends on the professionals involved.


For many SMEs, the most effective arrangement is not to replace the accountant but to add CFO-level expertise where financial planning and strategic decisions require more attention.

How Much Do Fractional CFO Services Cost?

There is no single fee for fractional CFO services because the work varies between businesses.


The cost may depend on:


  • Business size and financial complexity
  • Number of entities
  • Condition of existing financial records
  • Scope of responsibilities
  • Frequency of meetings
  • Reporting requirements
  • Forecasting and modelling needs
  • Fundraising or transaction support
  • Level of involvement required from the CFO


Some engagements use a fixed monthly retainer, while others are priced according to agreed hours, days or project deliverables.


A business that needs a monthly performance review and updated cash-flow forecast will generally require a different level of support from one preparing for an acquisition or a funding round.


When comparing proposals, look at the services and responsibilities included rather than focusing only on the headline fee.


You should also establish whether additional work, such as investor due diligence or a major financial model, will incur separate charges.

When Should an SME Consider Hiring a Fractional CFO?

There is no fixed revenue threshold that determines when an SME needs fractional CFO support.


The more useful question is whether the business has outgrown its current approach to financial management.


You may want to consider the service if:


  • You regularly experience unexpected cash-flow pressure.
  • Financial reports arrive too late to support important decisions.
  • Revenue is growing, but profitability remains unclear.
  • You are planning a significant investment or expansion.
  • You need more reliable budgets and forecasts.
  • Your accountant maintains the records, but no one provides strategic financial analysis.
  • Your finance manager is overloaded with operational responsibilities.
  • You are preparing for fundraising or discussions with lenders.
  • You need senior financial expertise without hiring a full-time CFO.


These situations do not automatically mean a fractional CFO is the right solution. First, identify the specific gap in your current finance function and determine whether it requires strategic leadership, improved accounting processes or both.

A Practical Example: Fractional CFO Support for a Growing SME

Consider a UK-based business that has grown steadily over the past few years.


It has an accountant who prepares the financial records and a small internal team that manages invoices and payments.


However, management is facing three problems.


First, the business cannot reliably predict its cash position over the next three months. Second, revenue is increasing, but the owners are unsure which services generate the strongest margins. Third, the company wants to recruit additional employees but does not know how much growth it can afford.


A fractional CFO engagement could focus on these specific requirements.


Month 1: Review the financial position

The CFO reviews available financial information, identifies reporting gaps, assesses cash flow and agrees on the key performance indicators management needs to monitor.


Month 2: Build forecasts and improve reporting

The CFO develops or refines cash-flow forecasts, reviews margins and establishes a regular management reporting process.


Month 3: Support business decisions

The CFO uses the updated information to assess recruitment costs, test revenue scenarios and help management decide whether the planned expansion is financially sustainable.


The exact timeline will vary according to the condition of the financial records, the complexity of the business and the scope of work.


The important point is that the engagement should be built around specific business requirements and measurable deliverables, rather than a generic list of financial services.

How to Choose the Right Fractional CFO Service

Before selecting a provider, consider the following questions.


What experience do they have with SMEs?


Look for experience relevant to your business model, industry and stage of growth. A provider who understands your commercial challenges may be better placed to identify the financial issues that matter most.


What exactly will they deliver?


Ask for a clear list of deliverables, including reports, forecasts, meetings and strategic responsibilities.

How will they work with your existing accountant?

Establish who prepares the financial data, who reviews it and how responsibilities will be divided.


How frequently will they be available?


Confirm the expected working hours or days, meeting schedule, response times and arrangements for urgent financial questions.


How will progress be measured?


Agree on objectives such as better cash-flow visibility, more timely reporting, improved forecasting or clearer profitability analysis. These measures make it easier to assess whether the engagement is meeting your needs.


Can the service adapt as the business grows?


Your requirements may change as the company expands, hires employees or prepares for investment. Confirm how the scope and fees can be adjusted.

Conclusion

Fractional CFO services give SMEs access to senior financial expertise without necessarily hiring a full-time CFO.


Depending on the engagement, the service can include cash-flow forecasting, budgeting, management reporting, profitability analysis, financial modelling, growth planning and fundraising support.


However, the real value is not simply receiving more reports or financial spreadsheets. It is having someone who can interpret the numbers, challenge assumptions and help management understand the financial implications of its decisions.


For businesses that already have basic accounting support but need stronger financial planning, a fractional CFO can fill an important gap.


The right engagement should start with the challenges your business needs to solve, define the deliverables clearly and establish how the CFO will work with your existing team.


Ultimately, fractional CFO services should give you a clearer understanding of your financial position, your future options and the decisions required to support sustainable growth.

Frequently Asked Questions

Yes. Small businesses can benefit when they need better financial forecasting, cash-flow visibility, profitability analysis or strategic financial advice but do not require a full-time CFO. Suitability depends on the complexity of the business and the decisions it needs to make.

There is no standard number of hours. The commitment depends on the business’s requirements, the complexity of its finances and the agreed scope. Some businesses need periodic strategic reviews, while others require more regular involvement.

The initial engagement may focus on understanding the financial position, identifying reporting gaps and establishing priorities. The time required to deliver meaningful improvements depends on the quality of existing information, the challenges being addressed and how quickly management implements recommendations.

Yes. A fractional CFO can review payment timing, receivables, supplier commitments, working capital and planned expenditure to help explain why cash is under pressure despite reported profits.

This depends on the engagement. Some providers include management accounts preparation, while others review financial statements prepared by the internal accountant or an external accounting firm. Statutory accounts and tax compliance should be confirmed separately.

Potentially. Depending on their experience and agreed responsibilities, a fractional CFO may help improve management reporting, prepare financial forecasts, review profitability and organise financial information for due diligence. Legal advice, transaction execution and specialist corporate finance work may require additional advisers.

The terms are sometimes used interchangeably. A Virtual CFO generally emphasises remote delivery, while a Fractional CFO describes access to CFO-level expertise on a part-time basis. In practice, responsibilities, time commitment and delivery arrangements matter more than the title.

The agreement should specify the scope of services, deliverables, meeting frequency, availability, fees, responsibilities, reporting arrangements, confidentiality and data access. It should also explain how additional projects or changes in scope will be handled.

Sources & References

  • OD Accountants: Fractional CFO Services - Management accounts, KPI reporting, cash-flow forecasting and commercial finance support.
  • Utile Accountancy: Fractional CFO Services - Budgeting, forecasting, management reporting and strategic decision support.
  • CFO Advisors: Fractional CFO Services for Startups - Financial planning, scenario modelling, cash management and investor reporting.
  • •Fractional CFO Services for UK SMEs - Practical context on cash-flow forecasting, financial modelling and SME finance leadership.
Categories
VIRTUAL CFO SERVICES

Virtual CFO vs Full-Time CFO: Which Is Right for Your Business?

As a business grows, financial decisions become more complex.

Managing cash flow, forecasting revenue, controlling costs and preparing financial reports can become increasingly difficult for a founder or existing finance team to manage alone.

At some point, a business may need CFO-level financial leadership.

But that creates an important question:

Should you hire a full-time CFO or work with a Virtual CFO?

Both options can provide senior financial expertise, but they operate differently.


A full-time CFO becomes a dedicated member of the leadership team, while a Virtual CFO provides senior financial support on a flexible or part-time basis.


The right choice depends on your business size, financial complexity, growth plans, existing finance team and the level of senior financial involvement you need.


This guide compares Virtual CFO and full-time CFO models and explains the factors businesses should consider before making a decision.

What Is a Virtual CFO?

A Virtual CFO is an experienced finance professional who provides CFO-level support without becoming a full-time employee of the business.


The relationship is generally structured around an agreed scope of work, reporting schedule and level of involvement.


Depending on the business, a Virtual CFO may support:


  • Financial forecasting
  • Budgeting and planning
  • Cash-flow management
  • Management reporting
  • Financial analysis
  • Business performance reviews
  • Working capital management
  • Scenario planning
  • Investor reporting
  • Banking and lender discussions
  • Fundraising preparation
  • Strategic financial decisions


A Virtual CFO can therefore provide senior financial guidance while working alongside an existing accountant, finance manager or outsourced accounting team.


The exact responsibilities depend on the business and engagement.


The broader fractional CFO model is increasingly being used by growing businesses that need senior financial expertise without immediately committing to a permanent executive hire.

What Is a Full-Time CFO?

A full-time CFO is a permanent member of the company’s leadership team.


Unlike a Virtual CFO, the CFO works exclusively for the business and is generally involved in financial decisions throughout the working week.


A full-time CFO may be responsible for:


  • Leading the finance function
  • Managing finance employees
  • Financial reporting
  • Budgeting and forecasting
  • Cash-flow management
  • Financial controls
  • Risk management
  • Business planning
  • Capital allocation
  • Investor and board reporting
  • Banking relationships
  • Fundraising
  • Acquisition or expansion planning
  • Finance strategy


The role can extend beyond financial reporting into strategic planning, financial control, risk management and broader organisational decision-making.


For larger or more complex organisations, this level of dedicated involvement can become increasingly important.

Virtual CFO vs Full-Time CFO: Key Differences

Factor Virtual CFO Full-Time CFO
Employment External finance professional or provider Permanent employee
Availability Agreed hours, meetings and reporting schedule Dedicated to the business
Cost structure Flexible service fee or retainer Salary plus employment costs
Scalability Scope can often be adjusted Fixed senior headcount
Expertise May bring experience across multiple businesses Develops deep knowledge of one business
Finance team management Depends on the engagement Usually a core responsibility
Strategic support Available according to agreed scope Embedded in day-to-day leadership
Recruitment No senior executive recruitment required Requires recruitment and onboarding
Commitment Flexible Long-term employment commitment
Best suited to Growing businesses needing senior expertise without a full-time hire Larger or complex businesses requiring dedicated finance leadership

The key difference is not necessarily the quality of financial expertise.


It is how much senior financial involvement the business requires and how often it needs it.

What Does a Virtual CFO Do?

The role of a Virtual CFO can vary considerably between businesses.


For one company, the priority may be improving cash-flow visibility.


For another, it could be preparing for investment or creating financial forecasts for expansion.


Common responsibilities include:


Financial Forecasting


A Virtual CFO can help businesses build financial forecasts based on revenue, costs, working capital and expected cash movements.


This can help management understand potential financial outcomes before making major decisions.


Cash-Flow Management


Profit does not necessarily mean that a business has sufficient cash available.


A Virtual CFO can help monitor expected inflows and outflows, identify potential cash shortages and improve working capital planning.


Cash-flow analysis is particularly important because understanding sources and uses of cash can help management assess the company’s financial position and future liquidity.


Management Reporting


Businesses need more than basic financial statements to understand performance.


A Virtual CFO can help develop management reports that highlight areas such as:


  • Revenue
  • Gross margin
  • Operating costs
  • Cash position
  • Working capital
  • Customer performance
  • Business-unit performance
  • Key financial KPIs


The objective is to give management information that can support better decisions.


Budgeting and Scenario Planning


A Virtual CFO can help management evaluate different financial scenarios.


For example:


What happens if revenue increases by 20%?


What happens if costs increase faster than expected?


Can the business afford to hire another team?


How much working capital will expansion require?


Scenario planning can make these decisions more measurable.


Strategic Financial Advice


A Virtual CFO can also act as a financial sounding board for business owners and management teams.


This can include reviewing pricing, investment decisions, financing options, expansion plans and overall financial performance.


Fractional CFOs can also support areas such as growth planning, pricing, capital raising and mergers or acquisitions, depending on the scope of the engagement.


What Does a Full-Time CFO Do?


A full-time CFO can perform many of the same strategic activities, but with a greater level of continuous involvement.


Because they are part of the organisation, they may also take responsibility for managing the finance function itself.


Leading the Finance Team


A full-time CFO can recruit, manage and develop finance employees.


They may oversee accountants, finance managers, accounts payable teams, accounts receivable teams and other finance professionals.


Building Financial Controls


As a business becomes larger, financial controls become increasingly important.


A CFO may establish processes around:


  • Financial approvals
  • Budget controls
  • Cash management
  • Reporting
  • Risk management
  • Internal controls
  • Financial policies


Working With Senior Management


A full-time CFO can participate in leadership meetings and provide financial input across the organisation.


This means finance becomes part of broader operational and strategic decision-making rather than operating as a separate function.


Managing Major Financial Events


A full-time CFO may also become particularly valuable during significant events such as:


  • Acquisitions
  • Business restructuring
  • Major fundraising
  • Expansion into new markets
  • Debt financing
  • Mergers
  • Large-scale investment
  • Preparation for a potential listing


These situations can require sustained financial involvement over an extended period.

What Is the Cost Difference?

Cost is often one of the first considerations when comparing a Virtual CFO with a full-time CFO.


However, businesses should look beyond the basic salary or monthly service fee.


A full-time CFO may involve:


  • Salary
  • Employer costs
  • Benefits
  • Recruitment fees
  • Bonuses
  • Technology and equipment
  • Training
  • Office costs
  • Holiday and absence cover


There is also the cost of hiring the wrong person or needing to replace the CFO later.


A Virtual CFO generally operates through an agreed service fee or retainer.


The cost can depend on:


  • Business size
  • Number of entities
  • Finance complexity
  • Reporting requirements
  • Frequency of meetings
  • Strategic requirements
  • Fundraising or transaction support
  • Existing finance team
  • Level of CFO involvement required


This can make the Virtual CFO model more flexible for businesses that need senior expertise but do not require a CFO working full-time.


Research and business commentary on fractional CFO models similarly highlight flexibility and the ability to access senior expertise without taking on a permanent full-time executive role.


The important point is to compare the total value and scope of the service, rather than simply comparing a monthly fee with an annual salary.

When Does a Virtual CFO Make Sense?

A Virtual CFO may be appropriate when the business has reached a point where financial decisions require senior expertise but the workload does not yet justify a dedicated full-time CFO.


This may include businesses that:


  • Are experiencing rapid growth
  • Need better financial forecasting
  • Have limited internal finance expertise
  • Need stronger cash-flow visibility
  • Are preparing for fundraising
  • Want better management reporting
  • Are considering expansion
  • Have an accountant but need more strategic guidance
  • Need financial support without adding another permanent executive
  • Have fluctuating finance requirements


For these businesses, hiring a full-time CFO may create more fixed capacity than the company actually needs.


A Virtual CFO can provide access to senior financial expertise while allowing the business to scale the engagement around its requirements.

When Does a Full-Time CFO Make Sense?

A full-time CFO may become more appropriate when finance has become a substantial and continuous part of the business.


This can happen when:


  • The finance team has become large
  • The business operates across multiple entities or markets
  • Financial transactions are highly complex
  • Management requires daily financial input
  • The CFO needs to manage a large finance function
  • The company is involved in major transactions
  • The business has complex funding requirements
  • Financial controls require continuous executive oversight
  • The CFO needs to participate regularly in leadership decisions


At this stage, having a dedicated CFO can provide the level of involvement and internal ownership that a part-time model may not be able to provide.


A full-time CFO can also build and lead a finance team as the organisation grows, making the role particularly relevant when financial leadership itself has become a major organisational function.

Virtual CFO vs Full-Time CFO: Which Is More Scalable?

Scalability is an important consideration for growing companies.


A full-time CFO provides dedicated capacity, but the cost and commitment remain relatively fixed.


If the company’s finance requirements change, the organisation may need to restructure the role or expand the finance team.


A Virtual CFO engagement can often be adjusted more easily.


For example:


Early growth → Financial reporting and cash-flow support


Faster growth → Forecasting, budgeting and management reporting


Fundraising → Investor reporting and financial modelling


Expansion → Scenario planning and financial strategy


Larger finance function → Additional strategic oversight


This flexibility can be useful when a business’s requirements are changing quickly.


However, scalability does not automatically mean outsourcing is better.


A business that needs daily leadership of a large finance team may ultimately benefit more from a full-time CFO.

Does a Virtual CFO Replace an Accountant?

Not necessarily.


A Virtual CFO and an accountant generally perform different roles.


An accountant may be responsible for areas such as:


  • Bookkeeping
  • Reconciliations
  • Financial records
  • Accounts preparation
  • Tax-related work
  • Transaction processing


A CFO operates at a more strategic level.


The CFO may use financial information to answer questions such as:


  • Why is cash flow changing?
  • Which products or services are most profitable?
  • How much can the business afford to invest?
  • Should the company raise finance?
  • What will happen if sales decline?
  • Where are costs increasing?
  • Can the business support further growth?


A business may therefore have an accountant handling financial records while a Virtual CFO provides senior financial oversight.

Can a Virtual CFO Work With an Existing Finance Team?

Yes.


This is one of the reasons the model can work well for growing businesses.


A company might already have:


  • An accountant
  • A finance manager
  • Bookkeeping support
  • Accounts payable staff
  • Accounts receivable staff


But the business may still lack senior financial leadership.


A Virtual CFO can work with the existing team rather than replacing it.


For example, the internal accountant may prepare the monthly financial information while the Virtual CFO reviews the results, identifies trends and prepares management recommendations.


This can allow the existing finance team to continue managing day-to-day activities while senior financial decisions receive additional attention.

What About a Fractional CFO?

The terms Virtual CFO and Fractional CFO are sometimes used interchangeably, although the exact meaning can vary between providers.


A Virtual CFO typically works remotely and provides CFO-level support according to an agreed scope.


A Fractional CFO may be more deeply embedded within the organisation and work with the business for a defined number of days or hours each month or week.


The distinction is not always consistent across the market.


Therefore, businesses should focus less on the title and more on:


  • Responsibilities
  • Availability
  • Reporting structure
  • Time commitment
  • Deliverables
  • Strategic involvement
  • Communication
  • Finance team responsibilities


The service agreement should make these expectations clear.

Can a Virtual CFO Support Fundraising?

Yes, depending on the provider and scope of the engagement.


Businesses preparing for fundraising may need help with:


  • Financial projections
  • Cash-flow forecasts
  • Financial models
  • Management reports
  • Investor information
  • Scenario analysis
  • Funding requirements
  • Business performance metrics


A Virtual CFO can help management prepare financially for discussions with investors or lenders.


Fractional CFOs are also commonly used during fundraising and other periods when a company needs more sophisticated financial modelling, reporting and planning.


However, the exact role of the CFO should be agreed in advance, particularly where legal, tax or audit advice is also required from other professional advisers.

What About Cash Flow and Working Capital?

Cash flow can become more difficult to manage as a business grows.


Revenue may increase while cash remains under pressure because of:


  • Slow customer payments
  • Increasing supplier commitments
  • Higher payroll costs
  • Stock requirements
  • Expansion costs
  • Capital expenditure
  • Financing repayments


A CFO can help management understand how these factors affect the company’s available cash.


A Virtual CFO can provide regular cash-flow forecasting and working capital analysis without requiring the business to hire a full-time CFO.


For businesses experiencing rapid growth, this can be particularly valuable because growth itself can create additional working capital requirements.


A Practical Example


Consider a growing professional services business with an established accounting team.


The accounts are being maintained correctly, but management does not have enough visibility into future cash flow.


The business is also considering opening another location and may seek external funding.


The company could hire a full-time CFO.


However, if the business does not yet require someone to manage a large finance department every day, this may be more capacity than it needs.


Instead, the company could work with a Virtual CFO to:


  • Build financial forecasts
  • Develop cash-flow reporting
  • Review margins
  • Create expansion scenarios
  • Prepare financial information for lenders or investors
  • Establish management reporting
  • Review performance with the leadership team


If the business continues to grow and eventually requires daily financial leadership, it could later transition to a full-time CFO.


This demonstrates an important point:


A Virtual CFO does not necessarily have to be a permanent alternative to a full-time CFO. It can also be a stage in the development of a company’s finance function.

Should You Hire a Virtual CFO or Full-Time CFO?

A useful way to approach the decision is to assess how much senior finance involvement your business actually needs.


Choose a Virtual CFO if:


  • You need senior financial expertise but not every day
  • Your existing finance team can handle routine accounting
  • You need better forecasting and cash-flow management
  • Your business is growing quickly
  • You want flexible access to CFO-level support
  • You are preparing for fundraising or expansion
  • You want to avoid adding another permanent senior employee
  • Your financial requirements may change over time


Consider a Full-Time CFO if:


  • Finance requires daily executive involvement
  • You have a substantial finance team to manage
  • The business has complex financial operations
  • The CFO needs to participate continuously in leadership decisions
  • You are managing major transactions
  • Financial controls require dedicated oversight
  • The business has reached a scale where a permanent CFO can take ownership of the entire finance function

What If You Are Not Ready for Either?

Not every growing business immediately needs a CFO.


Some companies may first need to strengthen their existing finance processes.


This could include improving:


Once these foundations are in place, management can better assess whether the next requirement is a finance manager, Virtual CFO, Fractional CFO or full-time CFO.


This is important because a CFO should not be expected to compensate for fundamentally weak financial processes indefinitely.

Questions to Ask Before Choosing a CFO Model

Before making a decision, businesses should consider the following.


How often do we need CFO-level input?


If the requirement is weekly or monthly strategic guidance, a Virtual CFO may be appropriate. If senior finance leadership is required every day, a full-time CFO may make more sense.


Who manages the existing finance team?


If there is already a capable finance manager, a Virtual CFO may be able to provide strategic oversight without taking over day-to-day management.


How complex are our financial operations?


Multiple entities, international operations, significant financing arrangements or complex reporting requirements may increase the need for dedicated finance leadership.


What are our growth plans?


Consider what the business is likely to need over the next two to five years rather than making the decision solely on current requirements.


Are we preparing for a major financial event?


Fundraising, acquisitions, refinancing or expansion may temporarily increase the need for CFO-level expertise.


What does success look like?


Define the outcomes you expect from the CFO role, such as better forecasting, improved cash-flow visibility, stronger reporting or support with strategic decisions.

Conclusion

The choice between a Virtual CFO and a full-time CFO is not simply a question of cost.


It is about matching the level of financial leadership to the needs of the business.


A Virtual CFO can provide flexible access to senior financial expertise, making the model particularly useful for growing businesses that need strategic guidance without requiring a full-time executive.


A full-time CFO provides dedicated leadership and can be the better option when finance has become a large, complex and continuous part of the organisation.


For some businesses, the decision may also change over time.


A company may begin with an accountant, add Virtual CFO support as it grows and eventually move to a full-time CFO when the finance function becomes large enough to require dedicated leadership.


The best approach is therefore to assess the complexity of your finance function, the level of senior involvement required and where the business is heading next.

Frequently Asked Questions

No. Both can provide senior financial leadership, but a Virtual CFO generally works on a flexible or part-time basis, while a full-time CFO is a permanent employee dedicated to the business.

Yes. A small or growing business may benefit when it needs financial forecasting, cash-flow management, strategic reporting or senior financial advice but does not need a full-time CFO.

It depends on the engagement. Some Virtual CFO arrangements focus primarily on strategy and oversight, while others include management of existing finance teams. Responsibilities should be clearly defined before the engagement begins.

There is no universal schedule. Some businesses may need weekly meetings and regular reporting, while others may require more intensive support during fundraising, expansion or other major financial events.

Yes. A Virtual CFO can help businesses analyse cash inflows and outflows, prepare forecasts, review working capital and identify potential cash-flow pressures.

A transition may make sense when finance requires daily executive attention, the finance team becomes significantly larger, financial operations become more complex or the business needs a dedicated CFO to lead its finance function.

Not necessarily. A finance manager may oversee day-to-day finance operations, while a Virtual CFO focuses on strategic financial planning, forecasting, performance analysis and senior decision-making.

Yes. A Virtual CFO can provide strategic oversight while an outsourced accounting provider handles bookkeeping, reconciliations, accounts payable, accounts receivable or other operational finance activities.

Not necessarily. The decision should depend on the complexity and level of financial involvement required. A larger business with relatively straightforward finance requirements may still benefit from flexible external support, while a complex organisation may require a dedicated CFO.

Look for relevant industry experience, strong financial planning skills, experience with businesses at a similar stage, clear reporting processes and the ability to work effectively with your existing finance team. The scope of responsibilities and expected deliverables should also be clearly defined.

Sources & References

  • Forbes: Why More Founders Are Turning To Fractional CFOs Before They Scale
  • Forbes: A Fractional CFO Can Offer Businesses Real World Experience Without A Long-Term Commitment
  • Forbes: The ROI Of Hiring Fractional CFO Services To Transform Your Business
  • Forbes: The Right Time To Hire A CFO: The Fractional Approach For Startups And Scaleups
  • CFA Institute: Analyzing Statements of Cash Flows II
Categories
Accounts Receivable

In-House vs Outsourced Accounting: Which Is Better for Growing Companies?

As a business grows, its accounting requirements usually grow with it.

More customers can mean more invoices. More employees can mean more payroll and expenses. Increasing revenue can bring greater reporting, forecasting and compliance requirements. Eventually, many businesses reach a point where they need to decide whether to continue expanding their internal finance team or outsource some or all of their accounting function.

This creates an important question:

Is in-house accounting or outsourced accounting better for a growing company?

There is no single answer for every business. The right approach depends on your size, transaction volume, internal expertise, growth plans, budget and the level of financial support your management team needs.


This guide compares both models and explains the key factors growing companies should consider before making a decision.

What Is In- House Accounting?

In-house accounting means employing finance professionals directly within your business.


Depending on the company’s size, an internal finance function might include:


  • Bookkeepers
  • Accounts assistants
  • Accountants
  • Finance managers
  • Financial controllers
  • Finance directors


An internal team may handle day-to-day bookkeeping, accounts payable, accounts receivable, payroll, reconciliations, management accounts, financial reporting and other finance activities.


Benefits of In-House Accounting


Having an internal team can provide direct access to finance professionals who understand the business and its operations.


Potential benefits include:


  • Direct communication with finance staff
  • Greater day-to-day control
  • Employees dedicated to the business
  • Internal knowledge of customers and suppliers
  • Immediate access to financial information
  • The ability to build a finance function around specific requirements


For companies with complex financial processes or significant internal finance requirements, having dedicated employees can be valuable.


Challenges of In-House Accounting


Building an internal accounting department also comes with additional responsibilities and costs.


Businesses may need to cover:

  • Salaries
  • Recruitment costs
  • Employer costs
  • Benefits
  • Training
  • Software
  • Office resources
  • Holiday and absence cover
  • Professional development


There is also a recruitment challenge. Finding experienced accounting professionals can take time, particularly when a business needs specialist skills rather than basic bookkeeping support.

What Is Outsourced Accounting?

Outsourced accounting involves using an external provider to manage some or all of your accounting activities.


Depending on the service arrangement, this may include:


  • Bookkeeping
  • Accounts payable
  • Accounts receivable
  • Bank reconciliation
  • Management accounts
  • Financial reporting
  • Payroll support
  • Cash-flow reporting
  • Month-end processes
  • Finance administration


Some businesses outsource one specific function, while others use an external provider as an extension of their entire finance team.


This makes outsourcing particularly flexible for growing companies whose requirements are changing.

In-House vs Outsourced Accounting: Key Differences

Factor In-House Accounting Outsourced Accounting
Employment Direct employees External finance provider
Recruitment Business manages hiring Provider manages finance talent
Costs Salaries and employment costs Service or agreed monthly fees
Scalability Requires additional recruitment Capacity can often be adjusted
Expertise Depends on internal team Access to wider finance expertise
Management Directly managed internally Managed through provider relationship
Technology Business usually provides systems Provider may provide or support technology
Continuity Dependent on internal staff Provider can provide team-based support
Flexibility Changes may require recruitment Services can often be adjusted
Strategic support Depends on internal expertise May be available as an additional service

The important point is that outsourcing does not necessarily mean losing control.


A well-structured outsourced accounting arrangement can give management access to financial information while transferring routine finance responsibilities to an external team.

Why Growing Companies Reconsider Their Accounting Model

The accounting structure that worked for a small business may not work as the company becomes larger.


A founder may initially manage bookkeeping themselves or use a part-time bookkeeper.


As sales increase, however, the volume of financial transactions also increases.


The business may eventually need:


  • More frequent reporting
  • Better cash-flow visibility
  • Stronger financial controls
  • Faster month-end reporting
  • More sophisticated forecasting
  • Better accounts receivable management
  • More support for management decisions


At this stage, the question is not simply whether accounting should be outsourced.

The bigger question is:

What finance capabilities does the business actually need?

The Cost of In-House Accounting


Cost is often one of the biggest factors in the decision.


An internal accountant’s salary is only one part of the overall cost of employing a finance team.


Businesses may also need to account for recruitment, employer costs, benefits, software, training, equipment and management time.


As the finance function becomes more sophisticated, the business may need multiple employees with different skill sets.


For example, a growing company could eventually require:


  • Accounts payable support
  • Accounts receivable support
  • Management accounting
  • Financial control
  • Financial planning and analysis


Building all these capabilities internally can be expensive.


The Cost of Outsourced Accounting


Outsourced accounting typically operates through an agreed service fee.


The exact cost depends on factors such as:


  • Transaction volume
  • Number of entities
  • Services required
  • Reporting requirements
  • Accounting software
  • Payroll requirements
  • Complexity of the business
  • Level of financial expertise required


The key advantage is that businesses can often access a wider range of expertise without hiring a full internal department.


However, businesses should compare providers based on the total scope and value of the service, rather than simply choosing the lowest monthly fee.


Can Outsourcing Improve Cash-Flow Management?


Accounting and cash flow are closely connected.


A business may report strong revenue while still experiencing pressure if customers are slow to pay.


Accounts receivable management is therefore an important part of a growing company’s finance function.


For a deeper explanation, see The Impact of Accounts Receivable on Cash Flow Statements.


A stronger accounting process can help management understand:


  • What customers owe
  • When payments are expected
  • Which invoices are overdue
  • How much cash is available
  • What payments are due
  • How working capital is changing


This information can make cash-flow planning more effective.

What About Accounts Receivable?

Accounts receivable can become increasingly time-consuming as a company grows.


More customers and higher sales volumes can result in more invoices to monitor and collect.


Some businesses choose to keep their core accounting function in-house while outsourcing accounts receivable or credit control.


These are related but distinct services.


Accounts Receivable Outsourcing vs Credit Control Outsourcing explains the differences between the two models and the types of support each can provide.


This can be particularly relevant for businesses that have a capable internal finance team but need additional capacity to manage customer collections.


Is Outsourced Accounting Secure?


Security is another important consideration when using an external accounting provider.


An outsourced finance provider may have access to commercially sensitive financial information, customer records and other business data.


Before outsourcing, businesses should understand how the provider manages:


  • Data access
  • User permissions
  • Confidential information
  • Data processing
  • Cybersecurity
  • Backups
  • Staff access
  • Data retention
  • Security incidents


Businesses should also understand their contractual responsibilities and those of the external provider.


For businesses considering outsourcing specifically for accounts receivable, our guide Is Accounts Receivable Outsourcing Secure? Data Protection and Compliance Explained provides further information about security and compliance considerations.

Can Outsourced Accounting Scale With Growth?

Scalability is one of the main reasons growing companies consider outsourcing.


An internal finance team generally grows through recruitment.


If transaction volumes increase significantly, the company may need another accounts assistant, accountant or finance manager.


With an outsourced model, the provider may be able to increase the level of support without the company having to recruit another permanent employee.


For example:


Small business → Bookkeeping support


Growing business → Bookkeeping + accounts payable + accounts receivable


Larger business → Full accounting support + management reporting


Established business → Accounting + financial planning and strategic finance support


The exact structure varies between providers, but the principle is that the finance function can develop alongside the business.

What About Strategic Financial Support?

Day-to-day accounting and strategic financial planning are not the same thing.


Accounting tells management what has happened financially.


Strategic finance can help management understand what the numbers mean for future decisions.


As businesses grow, they may need support with:


  • Financial forecasting
  • Budgeting
  • Scenario planning
  • Business performance analysis
  • Cash-flow forecasting
  • Management reporting
  • Investment planning
  • Growth planning


This is where services such as fractional CFO and outsourced FP&A support can become relevant.


Our guide to Fractional CFO vs Outsourced FP&A: Key Differences Explained explains how these services differ and where they can fit within a growing company’s finance strategy.


This distinction is important because a business may not need to choose simply between a junior internal accountant and a large outsourced finance function.


It may need a combination of operational accounting and strategic financial expertise.

When Does In-House Accounting Make Sense?

An internal accounting team may be appropriate when:


  • The business has high transaction volumes
  • Finance processes are highly specialised
  • Management requires frequent internal interaction
  • There is a need for dedicated finance employees
  • The company has the resources to recruit and retain accounting professionals
  • Finance is a major operational function
  • The business requires substantial internal financial control


For some organisations, building a dedicated internal finance department can be a natural part of growth.

When Does Outsourced Accounting Make Sense?

Outsourcing may be worth considering when:


  • The company does not need a full-time finance department
  • Finance workloads fluctuate
  • Recruitment is difficult
  • The business wants access to specialist expertise
  • Management wants to reduce finance administration
  • The company is growing quickly
  • Existing finance staff are overloaded
  • The business wants a scalable finance function


Outsourcing can also be useful when a company needs additional support without committing immediately to permanent recruitment.

What About a Hybrid Accounting Model?

Businesses do not necessarily have to choose one model exclusively.


A hybrid approach combines internal finance employees with outsourced support.


For example, a company might keep a finance manager internally while outsourcing:


  • Bookkeeping
  • Payroll
  • Accounts payable
  • Accounts receivable
  • Credit control
  • Management reporting


Alternatively, a business might maintain transactional accounting internally while using external specialists for forecasting and strategic finance.


A hybrid structure can therefore provide internal oversight while giving the business access to external capacity and expertise.


A Practical Example

Consider a growing UK company with 50 employees.


The business has an internal finance manager and one accounts assistant. As sales increase, the accounts assistant is spending more time processing invoices and following up outstanding payments.


The finance manager is increasingly pulled into administrative work instead of focusing on reporting, forecasting and business planning.


The company has several options.


It could hire another internal finance employee.


It could outsource specific activities such as bookkeeping or credit control.


Or it could outsource a wider part of the accounting function while retaining the finance manager internally.

The right choice depends on the company’s workload, budget, internal expertise and future plans.


The important point is to assess which finance activities are creating the greatest pressure before deciding what to outsource.

Questions to Ask Before Outsourcing Accounting

Before selecting an outsourced accounting provider, consider:


What services do you actually need?


Do you need bookkeeping, accounts payable, accounts receivable, management accounts or a complete finance function?


How will the provider communicate with your team?


Establish how often you’ll receive reports and who will be your main point of contact.


Which accounting software do they support?


Make sure the provider can work with your existing systems or provide a suitable alternative.


How will financial data be protected?


Ask about access controls, data security, confidentiality and data-processing arrangements.


Can the service scale?


Your finance requirements may change considerably over the next two to five years.


What happens during staff absence?


Understand how the provider maintains continuity if an assigned team member is unavailable.


What KPIs will be reported?


Agree on measurable outcomes rather than relying solely on general service descriptions.


How Should Growing Companies Decide?


Instead of asking whether in-house or outsourced accounting is universally better, businesses should assess their own requirements.


Consider these factors:


Business size: How complex is the current finance function?


Growth rate: How quickly are transaction volumes increasing?


Internal expertise: Do existing employees have the required skills?


Cost: What is the total cost of building and maintaining an internal team?


Scalability: How easily can the finance function adapt to future growth?


Control: How much direct internal oversight is required?


Technology: Which accounting and reporting systems are already in place?


Strategic requirements:

Does management need forecasting, FP&A or CFO-level support?


These factors provide a more useful basis for decision-making than simply comparing monthly costs.

Conclusion

For growing companies, the choice between in-house and outsourced accounting depends on the company’s current needs and future plans.


In-house accounting can provide direct control, dedicated employees and deep internal business knowledge.


Outsourced accounting can provide flexibility, scalability and access to a broader range of finance expertise without requiring a large permanent team.


A hybrid model can combine the two, allowing businesses to retain important finance responsibilities internally while outsourcing activities where external capacity or specialist expertise adds value.


The most effective approach is therefore not necessarily about choosing one model permanently. It is about building a finance function that can support the business as it grows.

Frequently Asked Questions

It can be, particularly when a business does not require a full-time accounting team. However, costs depend on the services required, transaction volumes and complexity. Businesses should compare the total cost of each model rather than salary or monthly fees alone.

Yes. Outsourcing can allow smaller businesses to access accounting expertise without building a large internal finance department. The level of support can often be adjusted as the company grows.

Depending on the provider, businesses can outsource bookkeeping, accounts payable, accounts receivable, credit control, reconciliations, management accounts, payroll support and financial reporting.

Yes. A hybrid model can allow an internal accountant or finance manager to retain oversight while external providers handle selected accounting activities.

It can be, provided businesses select an appropriate provider and establish suitable controls around data access, confidentiality, security and data processing. Security requirements should be assessed before entering into an outsourcing arrangement.

There is no fixed revenue threshold. Businesses may consider outsourcing when finance workloads are increasing, internal staff are overloaded, recruitment is difficult or management requires additional specialist expertise.

It can. The exact scope depends on the provider and service agreement. Accounts receivable may include invoicing, payment allocation, reconciliation, reporting and collections.

Some providers offer additional FP&A or fractional CFO services alongside accounting. These can support forecasting, budgeting, scenario planning and wider financial decision-making.

Categories
Real Estate

What Will Shape London Real Estate Over the Next Decade?

London real estate has never been short of confident predictions. The difficult part is knowing which ones will still sound sensible after the next interest-rate decision, planning announcement or investment committee meeting.

That makes informed conversation especially valuable. On 13 October 2026, Bisnow’s London State of the Market will bring together senior figures from investment, development, finance, asset management, technology and professional services to examine what could shape the capital’s property market over the next decade.

The event also marks ten years of Bisnow in the UK. Rather than looking backwards, the programme focuses on the questions facing the market now: where capital is moving, whether new development remains viable, how buildings must perform for occupiers and which sectors may attract the next wave of investment.

Unison Direct is an official sponsor of the event.

A keynote grounded in London’s transformation

The day begins with Sir George Iacobescu CBE, Executive Chairman of St John’s Wood Square. During more than three decades at Canary Wharf Group, Sir George oversaw over 30 million square feet of development across East London, the City and the South Bank.


His opening keynote will be moderated by Mike Phillips, UK Editor at Bisnow. It should provide a suitably broad starting point for a programme concerned with London’s next phase of growth. Few people have had a closer view of how large-scale investment, infrastructure and development can alter the economic geography of a city.

Taking the temperature of the London market

The first panel, “London State of the Market”, brings together leaders with experience across investment, listed property, sustainability, finance and transactions.


Speakers include Nick Leslau, Chairman of Prestbury Investments; Paul Tebbit, Global Co-Head of Real Estate at BlackRock; Andrew Jones, Co-Founder and CEO of LondonMetric; Sandra Fives, Chief Strategy Officer at Catalyst; and Stacy Eden, Head of Real Estate at RSM.


The discussion will be moderated by Jim Roberts, Partner at DAC Beachcroft.


Together, the panel represents several sides of the market. Investors want to know where value is returning. Operators need to understand changing occupier expectations. Finance leaders are watching risk, regulation and the cost of capital. Sustainability teams must translate long-term commitments into investable decisions. No pressure, then.

Can London still make development work?

Development viability receives its own session, and with good reason. Higher financing and construction costs, planning delays and pressure on returns have made the journey from attractive site to completed building considerably less straightforward.


“Building London: Development Viability and the Race to Delivery” will feature James Saunders, CEO of Battersea Power Station Development Company; Thomasin Renshaw, Managing Director of UK Development at Greystar; Nabeel Khan, CEO of Oxford Street Development Corporation; Barbara Marino, Development Director for London Commercial at Keltbray; and Mark Cunningham, Partner at Blick Rothenberg.


Joanna Preece, Construction Partner at Maples Teesdale, will moderate the discussion.


The panel combines experience in regeneration, residential development, construction, taxation and commercial property. Expect practical debate around viability, finance, delivery risk and what must change if London is to meet its development and housing ambitions.


Luke Armstrong, Regional President for the UK, Ireland, EMEA and Asia-Pacific at WeWork, will also deliver a presentation during the morning programme.

Buildings are becoming operating businesses

Owning a building is no longer simply a matter of collecting rent and keeping the lifts moving. Occupiers increasingly expect service, experience, connectivity, flexibility and measurable building performance.


“From Landlord to Operator: The Performance Revolution Reshaping How Assets Are Run and Valued” will explore this shift.


The panel includes Nick Deacon, Head of Offices, Europe at Nuveen Real Estate; Toby Courtauld, CEO of GPE; Katie Whipp, Chief Business Officer at Resustain; Laura Wilson-Brown, Managing Director of Asset Management at Hines; and David Woodman, Senior Customer Experience Strategy Director at Bewonder, a JLL company.


Vijay Sodiwala, Commercial Director at Wireless Infrastructure Group, will moderate.


Their discussion will consider how technology, sustainability, customer experience and service-led management influence tenant retention, operating performance and long-term asset value.

Where is capital moving?

The final panel turns to the question hovering over almost every real estate conversation: where is the money going?


“Where Capital Flows: The UK and the European Real Estate Opportunity” will feature Martin Towns, Global Head of Real Estate at M&G Real Estate; Robert-Jan Foortse, Head of European Property Investments at APG; John O’Driscoll, Global Co-Head of Investment Management at BNP Paribas REIM; Jon Neale, Director of Research and Insight at Montagu Evans; and Yash Dave, CEO of Unison Direct.


Anna Cartwright, Partner at Jones Day, will moderate.


The panel will examine investment appetite, the pricing of risk and the sectors attracting institutional conviction across the UK and Europe. It is scheduled from 2:30 PM to 3:10 PM, followed by post-event networking.

Unison Direct Event

Bisnow’s London State of the Market

Join Bisnow’s London State of the Market to connect with leading professionals and gain insight into the key developments shaping London's real estate market.

Date Tuesday, 13
October 2026
Time 10:00 AM – 3:30 PM BST
Venue InterContinental London Park Lane
Room Ballroom
Exclusive Offer
20%

Off Your Ticket

Unison Direct has a 20% ticket discount available for event visitors.

Get Your Tickets
● Offer available until 12 October 2026

To receive the promotional code, reply to our event invitation or contact the
Unison Direct team with the subject line “Bisnow discount code”.

We will send the code directly to you.

Frequently Asked Questions

The event takes place on Tuesday, 13 October 2026, from 10:00 AM to 3:30 PM BST.

The venue is InterContinental London Park Lane, One Hamilton Place, London W1J 7QY. The event will be held in the Ballroom.

The programme covers London’s real estate outlook, development viability, asset operations, occupier experience, planning, capital flows and investment opportunities across the UK and Europe.

Categories
Accounts Receivable

Accounts Receivable Outsourcing vs Credit Control Outsourcing: Which Delivers Better Results?

Late payments remain one of the biggest challenges facing UK businesses. Even profitable companies can experience cash flow pressure when invoices remain unpaid for weeks or months after their due date.

To improve collections and strengthen working capital, many organisations turn to outsourced finance support. However, a common question arises:

Should you outsource accounts receivable (AR) or outsource credit control?

While the two services are closely related, they are not the same.

Credit control outsourcing focuses primarily on collecting payments and reducing overdue invoices. Accounts receivable outsourcing covers a much broader range of activities, from invoice creation and payment tracking to collections, cash application, reporting and receivables management.


Understanding the difference can help businesses choose the right solution for their growth plans, customer base and cash flow objectives.

What Is Accounts Receivable Outsourcing?

Accounts receivable outsourcing involves delegating part or all of the invoice-to-cash process to an external provider.


Depending on the engagement, an outsourced AR team may handle:


  • Invoice generation and delivery
  • Customer account management
  • Payment tracking
  • Cash application
  • Accounts receivable reporting
  • Collections follow-up
  • Dispute management
  • Reconciliation
  • Aged debt reporting
  • Performance analysis


The goal is not simply to chase overdue invoices. Instead, AR outsourcing manages the entire receivables cycle and helps businesses maintain consistent control over incoming cash.

What Is Credit Control Outsourcing?

Credit control outsourcing focuses specifically on ensuring customers pay on time.


A specialist credit control provider typically manages:


  • Payment reminders
  • Customer follow-ups
  • Telephone collections
  • Email collections
  • Payment plan management
  • Overdue invoice monitoring
  • Debtor ledger reviews
  • Escalation procedures


Credit control is generally considered the collections portion of the receivables process rather than the entire receivables function. Its primary objective is reducing overdue debt and improving payment performance.

Accounts Receivable Outsourcing vs Credit Control Outsourcing: Key Differences

Although the terms are often used interchangeably, they address different business needs.

Area Accounts Receivable Outsourcing Credit Control Outsourcing
Scope End-to-end receivables management Payment collection and debtor management
Invoice Creation Yes Usually No
Cash Application Yes Limited
Reconciliation Yes Usually No
Reporting Extensive Collection-focused
Payment Chasing Yes Primary function
Customer Account Management Yes Limited
Strategic Insights Yes Minimal
Cash Flow Visibility High Moderate
Main Goal Optimise receivables performance Collect outstanding invoices

In simple terms:


Credit control outsourcing helps businesses get paid faster.


Accounts receivable outsourcing helps businesses manage and optimise the entire receivables process.

Why Receivables Matter More Than Ever

Accounts receivable directly affects business liquidity.


Every unpaid invoice represents revenue that has been earned but not yet converted into cash.


A poorly managed receivables process can result in:

  • Cash flow shortages
  • Higher borrowing costs
  • Increased bad debt exposure
  • Delayed growth initiatives
  • Reduced profitability


As explained in our guide on The Impact of Accounts Receivable on Cash Flow Statements, receivables management plays a critical role in maintaining healthy operating cash flow and supporting long-term business stability.


When businesses struggle with collections, the issue often extends beyond overdue invoices and begins affecting overall financial performance.

When Credit Control Outsourcing Makes Sense

Credit control outsourcing is often ideal when a business already has an effective invoicing process but struggles with collections.


Common warning signs include:


  • Rising debtor days
  • Increasing overdue invoices
  • Limited internal collection resources
  • Inconsistent payment follow-ups
  • Growing aged debt balances


A specialist credit control team introduces consistent collection procedures, structured follow-up schedules and escalation processes.


This disciplined approach often helps businesses reduce overdue balances without hiring additional internal staff.


Benefits of Credit Control Outsourcing


  • Faster collections
  • Reduced debtor days
  • Improved payment discipline
  • Consistent follow-up activity
  • Lower internal workload
  • Better customer communication
  • Flexible support during growth periods


For businesses with strong invoicing and reporting processes, credit control outsourcing can be a targeted solution.

When Accounts Receivable Outsourcing Makes Sense

Accounts receivable outsourcing is generally more suitable when businesses need support across the entire receivables lifecycle.


This is particularly common among:


  • Growing SMEs
  • Multi-location organisations
  • Businesses with high invoice volumes
  • Companies experiencing rapid growth
  • Organisations with lean finance teams


Rather than focusing only on collections, AR outsourcing creates a structured receivables operation that improves accuracy, visibility and cash flow performance.

Benefits of Accounts Receivable Outsourcing

  • End-to-end receivables management
  • Improved reporting accuracy
  • Better customer account visibility
  • Enhanced cash flow forecasting
  • Reduced administrative workload
  • Scalable finance support
  • Stronger receivables controls


For many businesses, AR outsourcing becomes a strategic finance decision rather than simply an operational one.

Which Service Has the Bigger Impact on Cash Flow?

Both services can improve cash flow, but they do so differently.


Credit control outsourcing improves collections performance by reducing overdue invoices and encouraging faster payments.


Accounts receivable outsourcing improves the broader receivables process, helping businesses issue invoices faster, monitor outstanding balances more effectively, resolve disputes promptly and strengthen reporting.


The result is often a more sustainable improvement in working capital management.


If your primary challenge is overdue debt, credit control may deliver the fastest improvement.


If your challenge extends across invoicing, reporting, reconciliation and collections, AR outsourcing typically provides greater long-term value.

Measuring Success: Which KPIs Matter?

Whether outsourcing AR or credit control, businesses should track measurable outcomes.


Important KPIs include:


Days Sales Outstanding (DSO)

Measures the average number of days it takes customers to pay invoices.


Accounts Receivable Turnover Ratio

Shows how efficiently receivables are collected during a period.


For a detailed explanation, see our guide on Accounts Receivable Turnover: What It Is & How to Calculate It.


Collection Effectiveness Index (CEI)

Measures how effectively receivables are collected over time.


Aged Receivables

Tracks outstanding balances by age category.


Cash Collection Rate

Measures actual cash collected versus expected collections.


These metrics provide a clearer picture of performance than simply reviewing overdue invoices.


Technology’s Role in Outsourced Receivables


Modern outsourcing providers rely heavily on technology.


Today’s AR and credit control teams commonly use:


  • Cloud accounting platforms
  • Automated reminders
  • Customer portals
  • Workflow automation
  • Real-time reporting dashboards
  • Collection management software
  • Secure document sharing


Technology enables faster processing, greater transparency and improved customer communication.


Businesses evaluating providers should assess both the people and technology supporting the service.

What About Data Security?

Many businesses worry about sharing financial information with an external provider.


However, outsourcing does not automatically increase risk.


A reputable provider should implement:


  • Role-based access controls
  • Multi-factor authentication
  • Data encryption
  • Secure file transfer
  • Audit trails
  • Data protection procedures
  • Regulatory compliance measures


As discussed in our article on Is Accounts Receivable Outsourcing Secure? Data Protection and Compliance Explained, businesses should evaluate security controls carefully before selecting any outsourcing partner.


Strong security practices are often more important than whether the team operates internally or externally.


A Practical Example


Consider a UK technology company generating 500 invoices per month.


The finance team spends significant time:


  • Creating invoices
  • Monitoring payments
  • Chasing customers
  • Updating ledgers
  • Producing reports


Overdue balances continue to grow despite these efforts.


Option 1: Credit Control Outsourcing


A specialist credit control provider focuses on overdue accounts and payment collections.


This improves collections performance but leaves invoice management and reporting responsibilities with the internal team.


Option 2: Accounts Receivable Outsourcing


An outsourced AR team manages invoicing, payment tracking, collections, reporting and reconciliations.


The business benefits from a more structured receivables process and improved visibility across the entire customer payment cycle.


The right solution depends on where the bottleneck exists.

How Does This Fit Within a Wider Finance Strategy?

Receivables management should not operate in isolation.


Many growing businesses combine AR outsourcing with broader financial support such as:


  • Financial planning and analysis
  • Cash flow forecasting
  • Budgeting
  • Management reporting
  • Strategic finance guidance


For organisations evaluating broader finance outsourcing options, our comparison of Fractional CFO vs Outsourced FP&A: Key Differences Explained provides additional insights into how finance leadership functions support business growth.


Together, these services help transform financial data into actionable business intelligence.

Accounts Receivable Outsourcing vs Credit Control Outsourcing: Which Delivers Better Results?

The answer depends on the problem you are trying to solve.


If your business struggles primarily with overdue invoices and payment collections, credit control outsourcing may be the most direct solution.


If your organisation needs support across invoicing, collections, reporting, reconciliation and cash flow visibility, accounts receivable outsourcing is likely to deliver broader operational and financial benefits.


Ultimately, the best outsourcing strategy is the one that aligns with your business goals, finance function maturity and growth plans.


Rather than asking which service is universally better, businesses should ask:


“Which solution addresses the specific weaknesses in our receivables process?”


That is where the most meaningful results are achieved.

Frequently Asked Questions

Accounts receivable outsourcing manages the full receivables cycle, including invoicing, collections, reconciliation and reporting. Credit control outsourcing focuses primarily on collecting payments and reducing overdue debt.

Yes. Credit control is typically one component of a broader accounts receivable outsourcing service.

Credit control outsourcing may deliver quicker collection improvements if overdue invoices are the main issue. Accounts receivable outsourcing often delivers broader long-term cash flow improvements.

Yes. Many SMEs outsource AR functions to improve collections, reduce administrative workloads and gain access to specialist finance expertise.

Common metrics include Days Sales Outstanding (DSO), Accounts Receivable Turnover Ratio, Collection Effectiveness Index, aged receivables and cash collection rates.

A reputable provider should implement strong security controls, including encryption, access controls, audit trails and data protection procedures.

Yes. Many providers offer standalone credit control outsourcing services focused specifically on payment collection and debtor management.

Industries with high invoice volumes, long payment cycles or complex customer billing arrangements often see the greatest benefits from accounts receivable outsourcing.

Categories
Accounts Receivable

The Impact of Accounts Receivable on Cash Flow Statements: A Complete UK Guide for 2026

For many UK businesses, strong sales and healthy profits do not always translate into strong cash flow. A company can generate significant revenue, report positive earnings, and still struggle to pay suppliers, employees, or operating expenses if customer payments are delayed.

This is where accounts receivable (AR) becomes critical.

Accounts receivable represents money owed to a business for products or services that have already been delivered but not yet paid for. While AR appears as an asset on the balance sheet, its impact extends far beyond financial reporting. It directly affects liquidity, working capital, and operating cash flow.

As economic uncertainty, inflationary pressures, and extended payment terms continue to challenge UK businesses in 2026, understanding the relationship between accounts receivable and cash flow statements has become increasingly important.

In this guide, we explain how accounts receivable affects cash flow statements, why finance teams monitor AR closely, and how businesses can improve cash flow through better receivables management.

What Is Accounts Receivable?

Accounts receivable refers to outstanding invoices owed by customers who have purchased goods or services on credit.


For example, if a business completes a £15,000 project and offers 30-day payment terms, the sale is recognised immediately. However, until payment is received, the £15,000 remains in accounts receivable.


AR is common across many industries, including professional services, manufacturing, technology, logistics, and healthcare. While offering credit terms can support sales growth, excessive receivables can create significant cash flow challenges.

Understanding the Cash Flow Statement

The cash flow statement provides a record of how cash moves into and out of a business during an accounting period.


Under IAS 7 Statement of Cash Flows, cash movements are classified into three categories:

Cash Flow Category Purpose
Operating Activities Cash generated from normal business operations
Investing Activities Cash related to investments and asset purchases
Financing Activities Cash related to loans, borrowing, and equity funding

For most businesses, accounts receivable affects the operating activities section because it relates directly to customer revenue and collections.

Why Accounts Receivable Matters for Cash Flow

Many business owners focus heavily on revenue and profitability. However, cash flow often tells a different story.


Revenue is recognised when a sale occurs.


Cash is recognised when payment is received.


The difference between these two events creates accounts receivable.


This timing gap means a company may appear profitable while experiencing cash shortages.


A growing accounts receivable balance often indicates that cash is tied up in unpaid invoices, reducing the amount of working capital available for daily operations.

Where Accounts Receivable Appears on the Cash Flow Statement

Most UK businesses use the indirect method when preparing cash flow statements.


Under this approach, net profit is adjusted for:


  • Non-cash expenses
  • Depreciation and amortisation
  • Changes in working capital
  • Accounts receivable movements
  • Accounts payable movements
  • Inventory changes


Accounts receivable is one of the most significant working capital adjustments.

If Accounts Receivable Increases

When accounts receivable increases during a reporting period, operating cash flow decreases.


This occurs because the business has recognised revenue but has not yet collected the related cash.


Example


Opening Accounts Receivable: £50,000


Closing Accounts Receivable: £80,000


Increase in AR: £30,000


Although sales may have increased, £30,000 remains unpaid by customers.


As a result, the cash flow statement deducts the £30,000 increase from operating cash flow.


The business has earned the revenue, but the cash has not yet arrived.

How a Decrease in Accounts Receivable Improves Cash Flow

When accounts receivable decreases, the opposite occurs.


A reduction in receivables indicates that customers have paid outstanding invoices, bringing cash into the business.


Example


Opening Accounts Receivable: £80,000


Closing Accounts Receivable: £55,000


Decrease in AR: £25,000


This £25,000 reduction increases operating cash flow because the business has successfully converted receivables into cash.


For many organisations, improving collections can have a greater impact on liquidity than generating additional sales.

The Relationship Between Accounts Receivable and Working Capital

Accounts receivable forms a major component of working capital.


Working capital is calculated as:


Current Assets – Current Liabilities


Because AR is a current asset, changes in receivables directly affect available working capital.


Businesses with excessive receivables may experience:


  • Cash shortages
  • Increased borrowing requirements
  • Delayed supplier payments
  • Difficulty funding growth initiatives
  • Reduced financial flexibility


Conversely, businesses that collect invoices efficiently often maintain stronger liquidity positions and healthier cash flow.

How Accounts Receivable Connects the Three Financial Statements

Accounts receivable links all three primary financial statements.


Profit and Loss Statement

Revenue is recognised when the sale occurs.


Balance Sheet


The unpaid invoice is recorded as accounts receivable.


Cash Flow Statement


The movement in receivables adjusts operating cash flow.


This connection explains why profit and cash flow are not always aligned.


A company may report record revenue while experiencing declining cash reserves if customer collections lag behind sales growth.

Key Accounts Receivable Metrics Finance Teams Should Track

Monitoring AR performance requires more than reviewing outstanding balances.


Leading finance teams track several important metrics.


Days Sales Outstanding (DSO)


DSO measures the average number of days it takes customers to pay invoices.


A rising DSO often signals collection issues and potential cash flow pressure.


Accounts Receivable Turnover Ratio


The AR turnover ratio measures how efficiently receivables are collected during a specific period.


Businesses looking to improve collection performance can explore our guide on Accounts Receivable Turnover: What It Is and How to Calculate It, which explains the formula, interpretation, and practical applications of this important metric.


Aged Receivables


Ageing reports categorise outstanding invoices by payment status.


Common categories include:


  • Current
  • 30 days overdue
  • 60 days overdue
  • 90+ days overdue


These reports help identify collection risks before they impact cash flow.


Collection Effectiveness


This metric measures how successfully a business converts outstanding receivables into cash.


Strong collection effectiveness often correlates with healthier operating cash flow.

Common Reasons Accounts Receivable Negatively Impacts Cash Flow

Several factors contribute to rising receivables balances.


Extended Payment Terms


Longer payment terms delay cash collection and increase working capital requirements.


Slow Invoicing Processes


Delayed invoicing postpones payment cycles and extends collection periods.


Poor Follow-Up Procedures


Businesses that fail to monitor overdue invoices often experience higher outstanding balances.


Customer Financial Difficulties


Customers experiencing financial challenges may delay payments, creating cash flow pressure for suppliers.


Rapid Growth


Growth can increase receivables significantly if sales outpace collection efforts.


While growth is positive, businesses must ensure that collection processes scale alongside revenue.

How AR Outsourcing Can Improve Cash Flow

Many organisations are turning to outsourced receivables management to improve collection performance and strengthen cash flow.


Outsourced AR teams can help businesses:


  • Accelerate invoice collections
  • Reduce overdue balances
  • Improve customer follow-up consistency
  • Enhance reporting visibility
  • Free internal finance teams for higher-value activities


Security remains a common concern when outsourcing finance functions. Businesses evaluating external AR support may find our article on Is Accounts Receivable Outsourcing Secure? Data Protection and Compliance Explained useful for understanding compliance, confidentiality, and data security considerations.

The Strategic Role of Financial Leadership

Improving cash flow often requires more than operational improvements.


Finance leaders use receivables data to:


  • Forecast cash flow
  • Plan working capital requirements
  • Support growth decisions
  • Evaluate financing needs
  • Improve liquidity management


As organisations scale, many seek additional strategic financial guidance. Our article on Fractional CFO vs Outsourced FP&A: Key Differences Explained explores how different finance leadership models help businesses manage cash flow, forecasting, and long-term planning.

Best Practices for Improving Accounts Receivable Performance

Businesses can strengthen cash flow by implementing several proven practices:


  • Establish clear payment terms
  • Invoice promptly after delivery
  • Automate invoice reminders
  • Conduct regular ageing reviews
  • Monitor DSO trends
  • Perform customer credit assessments
  • Escalate overdue accounts quickly
  • Use AR automation and reporting tools
  • Consider outsourcing collections when internal resources are limited


Small improvements in collection speed can generate significant cash flow benefits over time.

Conclusion

Accounts receivable plays a critical role in determining the financial health of a business. While revenue and profit remain important performance indicators, cash flow ultimately determines a company’s ability to operate, invest, and grow.


An increase in accounts receivable can reduce operating cash flow by tying up cash in unpaid invoices. A decrease in receivables, on the other hand, strengthens liquidity by converting outstanding balances into usable cash.


For UK businesses in 2026, effective accounts receivable management is no longer simply an accounting function. It is a strategic driver of cash flow, working capital efficiency, and long-term financial stability.


Organisations that actively manage receivables, monitor key metrics, and improve collection processes place themselves in a stronger position to maintain healthy cash flow and support sustainable growth.

Frequently Asked Questions

Most finance professionals recommend reviewing receivables weekly, while businesses with high transaction volumes may benefit from daily monitoring. Regular reviews help identify payment issues before they become significant cash flow problems.

The ideal DSO varies by industry and payment terms. Generally, businesses aim to keep DSO as close as possible to their agreed customer payment period.

Yes. Profitability is based on recognised revenue and expenses, while cash flow depends on actual cash movements. Delayed customer payments can create cash shortages even when a business is profitable.

Not necessarily. Professional AR providers typically use structured, customer-focused communication processes designed to maintain positive client relationships while improving collections.

Receivable trends provide insight into collection performance, customer payment behaviour, and overall liquidity. Rising receivables may indicate future cash flow risks.

Automation helps businesses issue invoices faster, send payment reminders automatically, track overdue balances, and generate real-time reporting, leading to improved collection efficiency.

Sources & References

  • IFRS Foundation – IAS 7 Statement of Cash Flows
  • IFRS Foundation – Statement of Cash Flows Educational Material
  • ICAEW – UK Financial Reporting Guidance
  • UK Government – Late Payment Reporting and Small Business Payment Practices
  • Sage – UK Cash Flow and Late Payment Research
  • Association for Financial Professionals (AFP)
Categories
Bookkeeping Services

Local vs Virtual: Which Outsourced Bookkeeping Model Is Best for Your Business?

Choosing an outsourced bookkeeping service is no longer simply about finding someone who can keep your accounts up to date. For many UK businesses, the bigger question is how that bookkeeping support should be delivered.

Should you work with a local bookkeeper who can meet you face-to-face? Or would a virtual bookkeeping team give you greater flexibility, technology and scalability?

Both models can work well. The right choice depends on your business size, transaction volume, reporting requirements, communication preferences, technology, budget and plans for growth.

For some businesses, local bookkeeping provides the personal relationship and face-to-face support they value. For others, a virtual bookkeeping model provides greater flexibility and access to specialist expertise without geographical limitations.

So, which outsourced bookkeeping model is best for your business?

The answer depends less on where your bookkeeper sits and more on how well the service fits the way your business operates.

What Is Local Outsourced Bookkeeping?

Local outsourced bookkeeping means hiring an external bookkeeping professional or firm that operates in your geographical area.


The relationship may include face-to-face meetings, on-site visits, document collection and regular in-person communication. Some local providers also use cloud accounting software, meaning local does not necessarily mean traditional or paper-based bookkeeping.


A local bookkeeper may handle:

The main attraction is often personal contact.


If you prefer sitting down with someone to discuss your finances, a local bookkeeping provider may feel more accessible.


However, geographical proximity does not automatically mean better service.

What Is Virtual Outsourced Bookkeeping?

Virtual bookkeeping is delivered remotely using cloud accounting software, secure communication platforms and digital document-sharing systems.


Instead of visiting your office, the bookkeeping team accesses authorised financial information remotely and communicates with you through email, video calls, messaging platforms or online project systems.


A virtual bookkeeping service can provide many of the same functions as a local provider, including:

  • Transaction processing
  • Bank reconciliation
  • Invoice management
  • Expense tracking
  • VAT bookkeeping
  • Accounts payable
  • Accounts receivable
  • Payroll support
  • Management reporting
  • Month-end close
  • Financial data preparation

The main difference is how the service is delivered rather than what bookkeeping work is performed.

For businesses already using cloud accounting software, virtual bookkeeping can be particularly convenient.


If you are considering a move towards digital bookkeeping, our guide to cloud bookkeeping vs traditional bookkeeping provides a useful comparison.

Local vs Virtual Bookkeeping: What Is the Difference?

The fundamental difference is the delivery model.


A local bookkeeper relies more heavily on geographical proximity and potentially face-to-face interaction. A virtual bookkeeper relies on digital systems and remote collaboration.

Factor Local Bookkeeping Virtual Bookkeeping
Location Usually nearby Can be anywhere
Face-to-face meetings Usually available Usually video calls
Communication In-person, phone and email Email, phone, video and online platforms
Technology May use cloud or traditional systems Usually cloud-based
Access to specialists Depends on local team Access to a wider talent pool
Scalability May depend on provider capacity Often easier to scale
Office visits Possible Not normally required
Recruitment limitations Geographical Less location-dependent
Cost structure May have higher local overheads Often more flexible
Best suited to Businesses valuing local contact Digitally enabled and growing businesses

Neither model is automatically better.


The important question is which model provides the right combination of accuracy, communication, technology, expertise and value.

Why Are More Businesses Considering Virtual Bookkeeping?

Technology has changed how financial information is created, stored and shared.


Cloud accounting platforms allow authorised users to access financial records without being in the same office. Bank feeds can import transactions, digital receipts can be uploaded remotely, invoices can be issued online and financial information can be reviewed without waiting for physical paperwork.


This makes remote bookkeeping much more practical than it was in the past.


The UK’s move towards digital tax reporting also makes reliable digital record-keeping increasingly important. Making Tax Digital for Income Tax began on 6 April 2026 for relevant sole traders and landlords with qualifying income above £50,000, with further thresholds being introduced in later years.


Businesses within the relevant rules need to maintain digital records and use compatible software for their submissions.


This does not mean every business needs a virtual bookkeeper.


However, it does mean businesses should consider whether their bookkeeping process is sufficiently digital, organised and accessible.

The Main Advantages of Local Bookkeeping

Local bookkeeping remains attractive for businesses that value personal relationships and physical accessibility.


1. Face-to-Face Communication


Some business owners simply prefer speaking with their bookkeeper in person.

A face-to-face meeting can make it easier to discuss unusual transactions, financial concerns or upcoming business decisions.

For owners who are less comfortable with technology, this can also make the bookkeeping process feel more straightforward.


2. Local Business Knowledge


A local bookkeeping firm may have experience working with businesses in the same area or industry.

They may understand local business networks, common operating models and the practical challenges faced by businesses nearby.

However, local knowledge should not be confused with accounting expertise. The quality and experience of the individual provider still matter more than their location.


3. Physical Document Handling


Businesses that still deal with physical paperwork may appreciate having someone nearby.

For example, a business with a large volume of paper receipts or documents may find occasional on-site support useful during a transition to digital bookkeeping.


4. Personal Relationships


A local provider may offer a highly personal service where the business owner works with the same individual or small team over a long period.

For some businesses, that continuity is valuable.

The Main Advantages of Virtual Bookkeeping

Virtual bookkeeping has become increasingly attractive as businesses become more comfortable with cloud-based financial systems.


1.  Access to a Wider Talent Pool


A virtual model removes geographical limitations.

Instead of choosing between the few bookkeeping providers within driving distance, a business can evaluate providers based on:

  • Experience
  • Qualifications
  • Industry knowledge
  • Technology
  • Service levels
  • Communication
  • Pricing
  • Scalability

This can make it easier to find the right expertise.


2. Flexible Support


Virtual bookkeeping can often be structured around the actual requirements of the business.

For example, a company may need:

  • Weekly bookkeeping
  • Monthly management accounts
  • VAT support
  • Year-end preparation
  • Accounts payable support
  • Accounts receivable support

The service can be adjusted as the business changes.


3. Cloud-Based Collaboration


A virtual bookkeeping team can work directly with your cloud accounting system and supporting documents.

This reduces the need to email spreadsheets back and forth or physically deliver paperwork.

It can also give business owners and accountants access to the same underlying financial information.


4. Easier Scalability


As transaction volumes increase, a virtual bookkeeping provider may be able to allocate additional resources without requiring the business to recruit another internal employee.

This can be particularly useful for growing businesses.


5. Potential Cost Efficiencies


A virtual provider does not necessarily need to maintain a local office close to every client.


That can create a more flexible cost structure.


However, businesses should not choose a virtual provider based on price alone. Cheap bookkeeping that produces inaccurate or delayed records can ultimately cost more.

Is Virtual Bookkeeping Secure?

Security is one of the most common concerns businesses have about remote bookkeeping.


The question is understandable because bookkeeping involves sensitive financial information.


However, the location of the bookkeeper is not what determines whether the process is secure.


A well-managed virtual bookkeeping arrangement should include appropriate controls such as:

  • Multi-factor authentication
  • Strong passwords
  • Role-based access
  • Individual user accounts
  • Secure file sharing
  • Access reviews
  • Data backup procedures
  • Secure devices
  • Clear staff permissions
  • Documented security processes

Businesses should also ask how the provider manages access to accounting software and financial records.


A local provider using poor security practices is not necessarily safer than a virtual provider with strong controls.

How does the bookkeeping provider protect my financial information?

Local vs Virtual Bookkeeping: Which Is More Cost-Effective?


Cost is an important consideration, but comparing hourly rates alone can be misleading.


A business should consider the total cost of the bookkeeping process.


This includes:

  • Bookkeeping fees
  • Software costs
  • Internal administration
  • Time spent correcting errors
  • Accountant clean-up fees
  • Time spent chasing documents
  • Management reporting
  • Payroll administration
  • VAT preparation
  • Staff recruitment
  • Training
  • Technology costs

A local bookkeeper may be more expensive but provide valuable face-to-face support.


A virtual bookkeeping provider may offer greater flexibility and access to a broader team.


The better question is therefore:


Which model gives the business accurate and timely financial information at the best overall value?


Which Model Is Better for Growing Businesses?


For many growing businesses, virtual bookkeeping can offer greater flexibility.


Growth often brings:

  • More customers
  • More invoices
  • More suppliers
  • More employees
  • More transactions
  • Additional bank accounts
  • VAT obligations
  • More reporting requirements
  • Greater cash-flow pressure

A bookkeeping arrangement that worked when the business had 50 transactions a month may become difficult when that number reaches 500.


Virtual outsourced bookkeeping can make it easier to increase support as transaction volumes and reporting requirements grow.


This is particularly relevant for startups.


If you’re building a new business, it’s worth considering bookkeeping early rather than waiting until financial records become difficult to manage. Our guide to outsourced bookkeeping for startups explores how outsourced support can help establish stronger financial processes from the beginning.


What About Businesses That Need Face-to-Face Support?


Virtual bookkeeping is not suitable for every business.


A local model may make more sense if:

  • The owner strongly prefers face-to-face meetings
  • The business has significant physical paperwork
  • Staff require on-site training
  • The finance process is not yet digital
  • The business operates through a local network
  • Management needs regular on-site support
  • The owner is uncomfortable with remote communication

Even then, the business does not necessarily need completely traditional bookkeeping.


A hybrid approach may be better.


For example, a local bookkeeper could visit quarterly while the majority of bookkeeping is completed digitally throughout the year.


Could a Hybrid Bookkeeping Model Be the Best Option?


For some businesses, the choice does not need to be completely local or completely virtual.


A hybrid model can combine the strengths of both.


For example:


Day-to-day bookkeeping: Virtual


Monthly reporting: Online


Quarterly financial review: Video meeting


Annual planning: Face-to-face meeting


Document management: Cloud-based


This gives the business digital efficiency while maintaining some personal interaction.


The hybrid model can be especially useful for businesses transitioning from traditional bookkeeping to cloud-based financial processes.

Local vs Virtual Bookkeeping for Different Types of Businesses

Different businesses have different needs.


Startups


Virtual bookkeeping is often a strong option.


Startups generally benefit from flexible support without the cost of building a full internal finance function.


Small Owner-Managed Businesses


Either model can work.


The decision may depend more on the owner’s communication preferences and comfort with technology.


Growing SMEs


Virtual or hybrid bookkeeping may provide greater scalability.


As transaction volumes increase, businesses often need more than basic transaction processing.


Businesses With Complex Financial Operations


Specialist virtual teams may have an advantage.


A wider team can potentially provide access to bookkeeping, accounting, reporting and other finance expertise.


Businesses With Heavy Physical Paperwork


Local or hybrid support may be useful.


However, moving towards digital record-keeping may eventually improve efficiency.

How Bookkeeping and Accounting Work Together

Choosing the right bookkeeping model does not eliminate the need for accounting expertise.


Bookkeeping focuses primarily on recording and organising financial transactions. Accounting uses that information for reporting, analysis, tax and decision-making.


In simple terms:

Bookkeeping tells you what happened. Accounting helps explain what the numbers mean.

That’s why choosing an outsourced bookkeeping provider should be considered alongside your wider finance requirements.


For a more detailed explanation, see our guide on bookkeeping vs accounting and why you need both.


A business may have excellent bookkeeping but still need an accountant for tax planning, statutory accounts, financial analysis or strategic advice.

How to Choose the Right Outsourced Bookkeeping Model

Before choosing local or virtual bookkeeping, ask these questions.


1.  How Complex Are Your Finances?


A business with simple transactions may have very different requirements from a growing company with multiple entities, VAT, payroll and large supplier networks.


2. How Important Is Face-to-Face Communication?


If you rarely need physical meetings, location may not be an important factor.


3. Are Your Financial Records Digital?


If you already use cloud accounting software, virtual bookkeeping may be easier to implement.


4. How Quickly Are You Growing?


Rapid growth makes scalability more important.


5. Do You Need Specialist Expertise?


If you need more than basic transaction processing, look for a provider with relevant accounting and industry experience.


6. What Level of Reporting Do You Need?


Consider whether you need only bookkeeping or also:

  • Management accounts
  • Cash-flow reporting
  • Budgeting
  • Forecasting
  • KPI reporting
  • Financial analysis


7. How Secure Is the Provider?


Ask about access controls, data security, software permissions and internal procedures.


8. Can the Provider Scale With You?


Changing providers every time your business grows can be disruptive.


Choose a partner that can support your future requirements as well as your current needs.

Questions to Ask an Outsourced Bookkeeping Provider

Before signing an agreement, ask potential providers:

  • Who will manage my bookkeeping?
  • Will I have a dedicated contact?
  • What accounting software do you support?
  • How frequently will my books be updated?
  • How are reconciliations reviewed?
  • What reports will I receive?
  • How do you protect financial data?
  • Can you support VAT requirements?
  • Can you work with my accountant?
  • What happens if transaction volumes increase?
  • Can you provide additional finance support later?
  • What is included in the monthly fee?
  • Are there additional charges for year-end or unusual work?


The answers can reveal more about the quality of the service than the headline price.

Local vs Virtual Bookkeeping : A Practical Example

Imagine a growing UK consultancy with eight employees.


The business currently uses a local bookkeeper who visits once a month. The arrangement worked well when the company was smaller.


However, the business now has:

  • More monthly invoices
  • Additional employees
  • More supplier payments
  • VAT reporting
  • Several recurring subscriptions
  • Growing customer receivables
  • A requirement for monthly management information

The business owner now needs financial information more frequently.


The issue is no longer whether the bookkeeper is local.


The issue is whether the bookkeeping process can keep pace with the business.


Moving to a virtual bookkeeping model could allow transactions to be processed regularly, bank feeds to be reconciled more frequently and management reports to be produced without waiting for the next physical visit.


Alternatively, the business could retain local support while using cloud systems and a wider virtual finance team.


The best solution depends on what the business actually needs.

Local vs Virtual: Which Outsourced Bookkeeping Model Is Best?

There is no universal winner.


Local bookkeeping is often best for businesses that prioritise face-to-face communication, local relationships and physical accessibility.


Virtual bookkeeping is often best for businesses that prioritise flexibility, digital collaboration, specialist expertise and scalability.


Hybrid bookkeeping can be the best option for businesses that want both digital efficiency and personal interaction.


For many UK businesses, the decision is increasingly moving away from “local or remote?” and towards:


“Which provider can give us accurate, timely and secure financial information in the way our business needs?”


That is the more important question.


As financial processes become increasingly digital and HMRC continues to expand Making Tax Digital, businesses should also consider whether their bookkeeping system is ready for future reporting requirements.


The right outsourced bookkeeping model should therefore do more than record transactions.


It should help your business maintain accurate records, improve financial visibility, support compliance and provide a foundation for growth.

Frequently Asked Questions

Not necessarily. Virtual bookkeeping can offer greater flexibility, scalability and access to wider expertise, while local bookkeeping can provide face-to-face communication and physical accessibility. The better option depends on the business’s needs.

It can be highly secure when the provider uses appropriate access controls, authentication, secure systems, data protection procedures and regular security reviews. Businesses should assess the provider’s security practices before sharing financial information.

Costs vary according to transaction volume, business size, software, reporting requirements and the level of support required. A simple bookkeeping service will generally cost less than a broader outsourced finance solution.

Yes. A virtual bookkeeper can work with your accountant by maintaining accurate financial records and providing access to relevant reports and supporting documentation. Clear responsibilities should be agreed between the bookkeeper and accountant.

Not necessarily. Cloud accounting software makes it possible for authorised bookkeepers and accountants to work remotely. If you are comfortable communicating digitally, a virtual bookkeeping model may provide more flexibility.

Yes. Businesses can move from local to virtual bookkeeping by reviewing their existing processes, selecting compatible software, organising financial records and establishing secure access for the new provider.

Yes. Virtual bookkeeping can be particularly useful for startups because it can provide professional financial support without requiring the business to employ a full-time bookkeeper from the beginning.

Consider your communication preferences, financial complexity, technology, transaction volume, budget and growth plans. If you want both digital efficiency and occasional personal interaction, a hybrid model may provide a good balance.

Sources & References

  • HMRC – Making Tax Digital for Income Tax
  • HMRC – Creating digital records for Making Tax Digital
  • HMRC – Choosing agents for Making Tax Digital
  • Unison Direct – Cloud Bookkeeping vs Traditional Bookkeeping
  • Unison Direct – Bookkeeping vs Accounting: Why You Need Both
  • Unison Direct – Outsourced Bookkeeping for Startups
Categories
Financial Planning & Analysis

AI in Finance: How Automation Is Transforming Accounting

Accounting has always relied on accurate data, consistent processes and careful review. But the way finance teams handle these responsibilities is changing.

Artificial intelligence (AI) and automation are now helping businesses process financial information faster, reduce repetitive work and generate more useful insights from their data.

For finance teams, this does not simply mean replacing manual tasks with software. The bigger opportunity is to move away from time-consuming administrative work and spend more time on analysis, planning and decision-making.

So, how exactly is AI changing accounting, and what does this mean for businesses?

What is AI in finance and accounting?

AI in finance refers to the use of artificial intelligence and related technologies to analyse financial data, automate processes, identify patterns and support decision-making.


Automation and AI are related, but they are not the same.


Traditional automation generally follows predefined rules. For example, an automated system may match an invoice with a purchase order or send a payment reminder when an invoice becomes overdue.


AI can go further. It can identify patterns in large amounts of data, highlight unusual transactions, support forecasting and generate summaries or reports.


Generative AI adds another layer by helping finance teams work with text and unstructured information. It can, for example, help draft management commentary, summarise financial results or support scenario analysis.


The distinction matters because businesses can use different technologies for different finance processes.

How is AI transforming accounting

AI is already being applied across several areas of finance and accounting. Some of the most practical applications include:


1. Automating data entry and processing

Manual data entry can take up a significant amount of time, particularly when finance teams deal with large numbers of invoices, receipts and financial documents.


AI-powered systems can extract information from documents and transfer relevant data into accounting or finance systems.


This can reduce repetitive work and minimise the risk of simple manual errors.


The benefit is not only speed. Finance professionals can spend less time moving information between systems and more time checking whether the information makes sense.


2. Making accounts payable more efficient

Accounts payable is another area where automation can make a noticeable difference.


AI-enabled workflows can help with:

  • Invoice capture and classification
  • Purchase order matching
  • Duplicate invoice identification
  • Approval workflows
  • Payment scheduling
  • Supplier queries
  • Exception identification


Instead of reviewing every transaction manually, finance teams can focus their attention on transactions that require investigation or approval.


This approach can make the accounts payable process more efficient while maintaining appropriate human oversight.

3. Improving bank reconciliation

Bank reconciliation can be repetitive, especially when businesses have a large number of transactions across multiple accounts.


AI and automation can help match transactions between bank statements and accounting records. Where the system identifies a straightforward match, the process can be completed automatically.


Unusual or unmatched transactions can then be highlighted for review.


This creates a more efficient workflow because accountants are not spending the same amount of time checking transactions that can already be matched confidently.

4. Supporting fraud and anomaly detection

AI can analyse large volumes of transactions and identify patterns that may be difficult to spot through manual review.


For example, a system may highlight:

  • Unusual payment amounts
  • Duplicate transactions
  • Unexpected changes in spending
  • Irregular supplier activity
  • Unusual expense claims
  • Transactions that differ from normal patterns


This does not mean AI can determine that a transaction is fraudulent on its own.


Instead, it can help finance teams identify areas that deserve closer attention.


AICPA & CIMA notes that AI tools can support risk assessment by examining large volumes of financial and procurement data for anomalies, errors and potential fraud.

5. Faster financial reporting

Financial reporting often involves collecting information from different systems, checking figures and preparing commentary.


AI can help automate parts of this process.


For example, finance teams can use AI to:

  • Pull together information from multiple sources
  • Identify significant variances
  • Summarise financial performance
  • Draft initial management commentary
  • Highlight changes in key financial metrics
  • Support recurring reporting processes


This can shorten reporting cycles and allow finance professionals to spend more time interpreting the results.


The goal is not simply to produce reports faster. It is to help businesses understand what the numbers mean.

How can AI improve financial forecasting?

Forecasting is one of the areas where AI can provide significant value.


Traditional forecasting often relies heavily on historical data, assumptions and manual spreadsheet analysis. AI can analyse larger datasets and identify patterns that may be difficult to identify manually.

Depending on the system and quality of the underlying data, AI can support:

  • Revenue forecasting
  • Cash flow forecasting
  • Expense forecasting
  • Working capital analysis
  • Demand planning
  • Scenario modelling
  • Budget variance analysis


For example, rather than simply reporting that costs have increased, an AI-enabled system may help identify which cost categories, locations or business activities are contributing to the change.


This gives finance leaders more information to support their decisions.


For businesses looking to strengthen their forecasting, scenario planning and financial decision-making capabilities, choosing the right FP&A outsourcing partner can provide additional expertise and support. Learn more about how to choose an FP&A outsourcing partner for your business.


However, forecasting is only as reliable as the data and assumptions behind it. AI-generated outputs still need to be reviewed and challenged by finance professionals. AICPA & CIMA specifically highlights the importance of verifying AI findings and maintaining professional judgement.

AI can move finance from reporting to insight

One of the biggest changes AI can bring to accounting is the shift from backward-looking reporting towards more forward-looking analysis.


Traditional accounting often answers questions such as:


What happened?


AI-supported finance can help teams explore additional questions:


Why did it happen?


What is likely to happen next?


What could happen if we change our assumptions?


Where should management focus its attention?

This is particularly valuable for CFOs and senior leadership teams.


McKinsey’s research into finance teams using AI found applications across areas such as forecasting, working capital management, reporting and cost optimisation. It also reported that finance professionals in some functions were spending less time on data processing and more time supporting business decisions.

What are the benefits of AI automation in accounting?

For businesses considering AI adoption, the potential benefits go beyond simply reducing manual work.


Greater efficiency: Automating repetitive processes can reduce the amount of time finance teams spend on routine administration.


Fewer manual errors: Automated workflows can reduce errors associated with repetitive data entry, calculations and transaction processing.


Faster access to information: AI can help finance teams process and analyse information more quickly, supporting faster reporting and decision-making.


Better financial visibility: When financial information is processed more consistently, businesses can gain a clearer view of cash flow, costs, performance and working capital.


More time for strategic work: Perhaps the most important benefit is the ability to redirect finance professionals towards analysis, planning and business partnering.


AICPA & CIMA describes AI as a technology that can automate routine processes while helping finance professionals focus more on analysis, insight and advisory work.

Does AI replace accountants?

This is one of the most common concerns surrounding AI in accounting.


The more realistic answer is that AI is likely to change the work accountants do rather than simply eliminate the profession.


Routine and repetitive activities are increasingly suitable for automation. But accounting also requires professional judgement, interpretation, communication, ethics and an understanding of business context.


For example, an AI system may identify an unusual transaction. An accountant still needs to determine why it happened, whether it is appropriate and what action should be taken.


Similarly, AI may generate a financial forecast, but a finance leader needs to assess whether the assumptions are reasonable and how the forecast should influence business decisions.


ACCA has highlighted that AI is expected to reshape how accounting tasks are completed, while human intervention remains important at critical points.


The role of the accountant is therefore becoming less focused on processing information and increasingly focused on interpreting it.

What are the risks of using AI in accounting?

AI offers significant opportunities, but businesses should not adopt it without considering the risks.


Data security: Financial information is highly sensitive. Businesses need to understand where data is stored, how it is processed and who can access it.


Data quality: Poor-quality financial data can lead to poor-quality AI outputs.


The principle is simple:


Better data leads to better analysis.


Lack of human oversight: AI can produce incorrect or misleading results. Important financial decisions should not be based solely on an automated output.


Integration challenges: AI tools need to work effectively with existing accounting, ERP, payroll, CRM and banking systems. Poor integration can create additional work rather than reducing it.


Skills gaps: Finance teams need to understand not only how to use AI tools but also how to review their outputs and identify potential limitations.


A 2025 AICPA & CIMA survey of 1,446 finance and accounting leaders and managers found that 88% believed AI would be the most transformative technology trend in accounting and finance over the following 12–24 months, while only 8% felt their organisation was very well prepared to manage the trend.


This highlights an important point: adopting AI is as much about people, processes and governance as it is about technology.

How should businesses start using AI in finance?

Businesses do not need to automate everything at once.


A more practical approach is to identify finance processes where automation can deliver a clear benefit.


Start by asking:


Which processes are repetitive?


Where are teams spending too much time on manual data processing?


Which tasks regularly create delays or errors?


Where would faster financial information improve decision-making?


From there, businesses can select one or two suitable processes and measure the results.


For example, a company might begin with invoice processing or bank reconciliation before moving into more advanced applications such as forecasting and scenario modelling.


This phased approach makes it easier to understand the technology, train employees and establish appropriate controls.

What does the future of AI in accounting look like?

AI is likely to become increasingly embedded into everyday finance processes.


The next stage will not simply involve individual AI tools performing isolated tasks. Businesses are increasingly exploring connected workflows where AI can help move information between processes, identify issues and support decisions.


This could mean finance teams spending less time collecting and preparing information and more time interpreting financial performance.


However, successful adoption will depend on having the right foundations in place.


Businesses will need:

  • Reliable financial data
  • Well-defined processes
  • Appropriate technology integration
  • Clear governance
  • Strong data security
  • Skilled finance professionals
  • Human review and accountability


PwC’s 2025 analysis highlighted a similar shift from AI experimentation towards focused finance workflows, measurable business outcomes and stronger governance, including human oversight.

Final Thoughts

AI is changing accounting, but its biggest impact may not be the automation of individual tasks.


The real opportunity is to create a finance function that can process information faster, identify important changes earlier and provide better insight to the wider business.


Routine accounting activities can increasingly be automated. This gives finance professionals more time to focus on the areas where human judgement matters most — financial planning, analysis, forecasting and strategic decision-making.


For businesses, the question is therefore not simply whether AI should be adopted.


It is where AI can create the most practical value, and how it can be introduced without compromising accuracy, security or professional judgement.


With the right approach, AI can become less about replacing finance teams and more about helping them work more efficiently and become stronger strategic partners to the business.

Sources & References

  • AICPA & CIMA – AI in Accounting and Finance: Navigating Rapid Change (AICPA & CIMA)
  • AICPA & CIMA – AI Resources for Accounting and Finance (AICPA & CIMA)
  • McKinsey – How Finance Teams Are Putting AI to Work Today (McKinsey & Company)
  • ACCA – AI Is Reshaping the Work of Accountants (ACCA Global)
  • AICPA & CIMA – Future-Ready Finance: Technology, Productivity and Skills Survey (AICPA & CIMA)
  • PwC – AI: Finance Is Shifting from Pilots to Performance (PwC)
Categories
Bookkeeping Services

Cloud Bookkeeping vs Traditional Bookkeeping: What UK Businesses Need to Know

Bookkeeping has always been one of the basic foundations of running a business. It records what comes in, what goes out, what is owed, what is due, and what needs to be reported. But the way bookkeeping is done has changed significantly.

For many UK businesses, the choice is no longer just about who keeps the books. It is also about how the books are maintained. Should the business continue with traditional bookkeeping methods, or move towards cloud-based bookkeeping software and digital workflows?

The answer depends on the business, its size, its reporting needs, and how quickly it wants access to financial information. But one thing is clear: UK tax and reporting systems are becoming more digital. This means cloud bookkeeping is no longer only a convenience. For many businesses, it is becoming part of staying organised, compliant, and ready for future reporting requirements.

What is traditional bookkeeping?

Many growing businesses reach a point where the founder, accountant, or internal finance manager can no longer answer every strategic finance question alone. The business may need to know whether it can afford to hire, how  Traditional bookkeeping usually refers to bookkeeping done through paper records, desktop software, spreadsheets, physical receipts, manual data entry, and periodic updates. In many small businesses, this may mean invoices are stored in folders, receipts are collected at month end, bank statements are downloaded manually, and records are updated only when the accountant or bookkeeper reviews them.


This approach can still work for very small businesses with simple transactions. It may also feel familiar to business owners who prefer physical records or have used the same process for years.


The challenge is that traditional bookkeeping can become slow and difficult to manage as the business grows. Information may be spread across emails, spreadsheets, folders, bank portals, and accountant files. This makes it harder to get a live view of cash flow, overdue invoices, expenses, VAT position, and business performance.


ong its cash runway is, which service line is most profitable, whether it is ready to raise funding, or what may happen if sales slow down.

These questions require more than accurate accounts. They require financial interpretation, planning, and leadership. This is where fractional CFO and outsourced FP&A support become relevant. But before choosing between them, it is important to understand what each role is designed to do.

What is cloud bookkeeping?

Cloud bookkeeping uses online accounting software to record, store, and manage financial information. Instead of keeping data on one computer or in physical files, records are stored securely online and can be accessed by authorised users from different locations.


Cloud bookkeeping may include bank feeds, digital receipt capture, invoice creation, expense categorisation, VAT records, payment tracking, reporting dashboards, and integration with other business tools. It can also allow the business owner, bookkeeper, accountant, and finance team to work from the same records rather than passing files back and forth.


The main value is not just that the data is online. The bigger value is that financial records can be updated more regularly, reviewed more easily, and used for decision-making sooner.


It is also important to understand the difference between bookkeeping and accounting, as bookkeeping provides the accurate financial records that accounting relies on for reporting, analysis, tax and business decision-making.

The main difference between cloud and traditional bookkeeping

The biggest difference is access to information.


Traditional bookkeeping often works in batches. Records may be updated weekly, monthly, quarterly, or close to tax deadlines. Cloud bookkeeping allows records to be updated more frequently through bank feeds, digital invoices, receipt uploads, and connected tools.


This does not mean cloud bookkeeping removes the need for human review. Software can automate parts of the process, but someone still needs to check accuracy, categorise transactions correctly, review exceptions, reconcile accounts, and understand what the numbers mean.


The difference is that cloud systems usually make the process faster, more visible, and easier to manage.

Why UK businesses are moving towards digital records

UK businesses are operating in a more digital compliance environment. HMRC’s Making Tax Digital programme already requires VAT-registered businesses to keep digital records and submit VAT returns using compatible software. HMRC guidance also states that Making Tax Digital for Income Tax applies from 6 April 2026 to relevant sole traders and landlords with total qualifying income from self-employment and property above £50,000. 


Companies House is also moving further towards software-based filing. From 1 April 2028, all UK registered companies will be required to file annual accounts using commercial software in iXBRL format. Companies House has confirmed that changes to accounts filing will not be introduced in April 2027 and will instead take effect from April 2028. 


These changes do not mean every business must use the same bookkeeping system. But they do show the direction clearly. Financial records are becoming more digital, structured, and software-led.

Cloud bookkeeping vs traditional bookkeeping: a practical comparison

Area

Cloud bookkeeping

Traditional bookkeeping

Record storage

Online, accessible to authorised users

Paper files, spreadsheets, or desktop systems

Access

Available from different locations

Usually limited to one location, device, or file owner

Updates

Can be updated regularly through bank feeds and digital tools

Often updated manually or in batches

Collaboration

Owner, bookkeeper, accountant, and finance team can work from the same records

Files often need to be shared, emailed, or transferred

Reporting

More timely dashboards and reports

Reports may depend on manual updates

Receipt handling

Digital upload and storage

Physical receipts or scanned files

Compliance readiness

Better aligned with digital reporting direction

May require extra work to meet software-based requirements

Risk

Depends on access control and cyber hygiene

Risk of lost records, version errors, manual mistakes

Best for

Growing businesses, multi-location teams, VAT registered businesses, digital workflows

Very small businesses with simple transactions and limited reporting needs

How cloud bookkeeping supports better cash flow visibility

Cash flow is one of the strongest reasons businesses move to cloud bookkeeping. Traditional records may show what happened after the fact. Cloud systems can help the business see what is happening closer to real time.


For example, a cloud bookkeeping setup can show customer invoices raised, invoices overdue, supplier bills due, bank balances, recurring payments, VAT liabilities, and cash movements in one place. This helps the business avoid relying only on the bank balance, which can be misleading if several payments are due soon.


Better visibility does not automatically solve cash flow problems, but it helps identify them earlier. A business can follow up on overdue invoices sooner, plan supplier payments better, and avoid being surprised by upcoming tax or payroll obligations.

How cloud bookkeeping improves collaboration

Yes, traditional bookkeeping can still work in some situations. A very small business with few transactions, limited reporting needs, and a simple structure may not need a complex cloud setup immediately. Some business owners may also prefer physical documents or have long-standing internal processes that still work adequately.


However, the business should be honest about whether the traditional process is still serving it well. If records are often delayed, receipts go missing, reports are only available at year end, or cash flow is unclear, the process may be holding the business back.


Traditional bookkeeping becomes less practical as the business grows, becomes VAT registered, adds employees, works with more suppliers, manages customer credit, or needs regular management information.

The security question

Some businesses worry that cloud bookkeeping is less secure because records are stored online. That concern is understandable, but security depends more on controls than on whether records are cloud-based or traditional.


Cloud bookkeeping can be secure when the business uses strong passwords, multi-factor authentication, named user accounts, role-based permissions, secure devices, regular access reviews, and reputable software providers. The UK’s National Cyber Security Centre says Cyber Essentials is a government-backed scheme that helps organisations protect themselves against common cyber attacks. GOV.UK also notes that Cyber Essentials is increasingly used by businesses, including leading UK banks, to support cyber security in supply chains. 


Traditional bookkeeping has its own risks. Paper records can be lost or damaged. Spreadsheets can be overwritten. Files can be emailed to the wrong person. Desktop software can become outdated or difficult to back up. The safer approach is not simply “cloud” or “traditional.” It is a controlled process with the right access, storage, review, and backup practices.

The role of automation

Cloud bookkeeping can automate many routine tasks, such as importing bank transactions, matching payments, capturing receipts, sending invoice reminders, and generating basic reports. This can save time and reduce manual effort.


However, automation should not be confused with full accuracy. Software may suggest a category, but the suggestion can still be wrong. Bank feeds may import transactions, but reconciliations still need review. A receipt may be captured digitally, but the expense still needs to be checked.


The best cloud bookkeeping setups combine automation with human oversight. The software improves speed and visibility. The bookkeeper or finance team ensures the records are correct, complete, and useful.

The business maturity question

Choosing between a fractional CFO and outsourced FP&A often depends on the maturity of the business.


An early-stage business may not need a fractional CFO every month. It may first need clean reporting, cash flow visibility, and a simple forecast. In that case, outsourced FP&A may be enough.


A scaling business with investors, lenders, multiple revenue streams, hiring plans, and more complex decisions may need CFO-level leadership. In that case, a fractional CFO may be more appropriate.


A larger SME may need both: a fractional CFO to guide finance strategy and outsourced FP&A to build the reporting and analysis engine beneath it.


The key is to match the support to the problem. If the main problem is that the business does not understand its numbers clearly enough, outsourced FP&A may be the right starting point. If the business already has visibility but needs senior financial leadership to guide decisions, a fractional CFO may be more suitable.

Cost difference between cloud and traditional bookkeeping

Traditional bookkeeping may appear cheaper at first if the business is only using spreadsheets or a simple desktop process. But the true cost should include time spent finding receipts, correcting errors, preparing records for the accountant, chasing missing information, and creating reports manually.


Cloud bookkeeping usually has a software subscription cost, but it may reduce admin time, improve collaboration, and make reporting easier. It may also reduce year-end clean-up work if records are maintained properly throughout the year.


The right comparison is not only subscription cost versus no subscription cost. The better question is: which approach gives the business accurate, timely financial information at a reasonable overall cost?

When cloud bookkeeping is usually the better choice

Cloud bookkeeping is usually a better fit when the business has regular transactions, VAT obligations, multiple bank accounts, employees, customer invoices, supplier bills, recurring costs, or a need for monthly reporting. It is also useful when the business works with an outsourced bookkeeper, accountant, or finance team.


It becomes especially valuable when leadership needs faster answers. If the owner needs to know current cash position, overdue invoices, monthly spend, tax exposure, or profitability by service line, cloud bookkeeping provides a stronger foundation than delayed manual records.


For growing UK businesses, cloud bookkeeping can also help prepare for a more digital reporting environment, including MTD requirements and future Companies House software filing.

When traditional bookkeeping may still be enough

Traditional bookkeeping may be enough for a very small business with low transaction volume, no VAT registration, simple expenses, and limited need for monthly reporting. It may also work as a temporary setup in the earliest stage of a business.


However, even in these cases, the business should keep records organised and compliant. Companies must keep accounting records, and self-employed individuals must also keep records of business income and expenses. If the business expects to grow, it is usually better to move towards a digital process before the records become difficult to manage.

How to move from traditional to cloud bookkeeping

Moving to cloud bookkeeping does not need to happen all at once. The business can start by reviewing its current process, identifying pain points, choosing suitable software, setting up a chart of accounts, connecting bank feeds, creating invoice templates, and defining who is responsible for reconciliation and review.


It is also important to clean up opening balances, migrate supplier and customer records carefully, set access permissions properly, and agree how receipts, invoices, and supporting documents will be stored. If an outsourced bookkeeper or accountant is involved, they should help set up the system in a way that supports both compliance and management reporting.


For startups, outsourcing bookkeeping can be a practical way to establish reliable financial processes from the beginning without immediately building a full in-house finance team.


Learn more about outsourced bookkeeping for startups and how it can support financial visibility and scalable financial processes.


A poor setup can create confusion later. A good setup can make bookkeeping simpler, cleaner, and more useful from the beginning.

What UK businesses should check before choosing cloud software

Before choosing a cloud bookkeeping system, a business should consider whether the software supports its structure, VAT needs, reporting requirements, bank feeds, payroll links, user permissions, receipt capture, accountant access, and future filing requirements.


The business should also check data security, backup practices, support availability, user training, integrations, pricing, and whether the software is compatible with relevant HMRC or Companies House filing requirements.


The right software should match the business, not the other way round. A simple business may not need an overly complex system. A growing business should avoid software that will become limiting after a year.

Building a bookkeeping process that supports the business

Cloud bookkeeping and traditional bookkeeping both aim to do the same basic job: keep financial records accurate and organised. The difference is in how quickly, clearly, and efficiently those records can be maintained and used.


For many UK businesses, cloud bookkeeping is becoming the more practical choice because it supports digital records, faster reporting, easier collaboration, and better cash flow visibility. It also aligns more naturally with the UK’s move towards software-based tax and company reporting.


Traditional bookkeeping may still work for very small or simple businesses, but it can become restrictive as transactions, compliance needs, and reporting expectations grow.


The best approach is not to choose cloud bookkeeping because it sounds modern. It is to choose the bookkeeping process that gives the business accurate records, timely information, secure access, and confidence in its numbers.


For growing businesses, that is increasingly likely to be cloud-based.

Sources & References

  • HMRC – Digital record-keeping direction for Making Tax Digital for Income Tax
  • GOV.UK – Get ready for MTD: an agent toolkit
  • GOV.UK – Companies House to bring in changes to accounts filing from April 2028
  • National Cyber Security Centre – Cyber Essentials overview